
═══════════════════════════════════════════
WEEKLY REGIME VERDICT
═══════════════════════════════════════════
NEUTRAL
Posture: 30–50% capital — cleanest setups only
Held from last week. SPY stayed above its 20 SMA and both indices still confirm Stage 2. Three of four conditions are still firing.
The verdict didn’t move. What moved was the floor underneath it: S&P 500 short-term breadth fell into washed-out territory for the first time since this report began, and the 10-year went to a new high on the same day the jobs report missed by two-thirds.
───────────────────────────────────────────
WHAT THE STRUCTURE SAYS
───────────────────────────────────────────
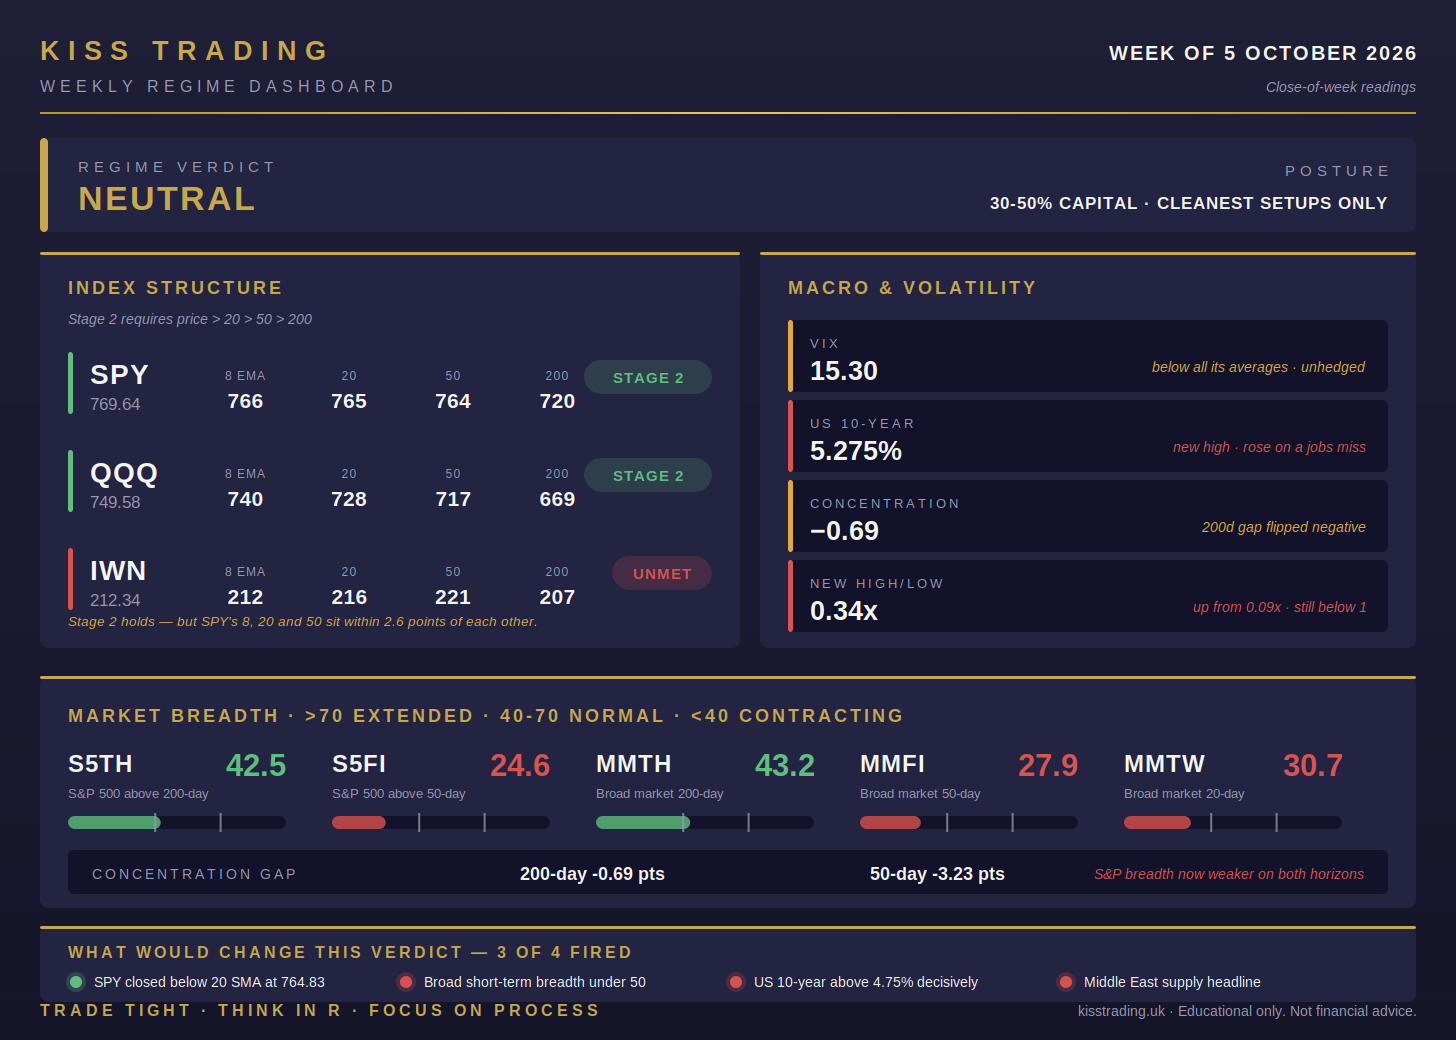
SPY closed at 769.64, above the 8 EMA at 766.25, the 20 SMA at 764.83, the 50 SMA at 763.70 and the 200 at 720.47. The order is correct. The spacing isn’t. Three of those averages now sit within 2.6 points of each other, and price is 0.62% above the 20 SMA. That’s a stack squeezed flat, holding its shape by very little.
QQQ is the opposite picture. It closed at 749.58, nine points clear of its 8 EMA and twenty-two clear of the 20 SMA. The Nasdaq 100 made a record close on Friday. Over the week, QQQ gained 0.7% while SPY lost 0.2%.
IWN is still broken. At 212.34 it sits on its 8 EMA, below the 20 SMA at 215.98 and the 50 SMA at 220.83, with the 20 under the 50. Small-cap value has now lagged for five straight weeks.
Key levels for the week:
→ SPY support: 764.83 (20 SMA), then 763.70 (50 SMA) · resistance: 772.65, Friday’s high
→ QQQ support: 740.46 (8 EMA), then 727.78 (20 SMA) · resistance: none, at record highs
───────────────────────────────────────────
WHAT BREADTH SAYS
───────────────────────────────────────────
S5FI closed at 24.65. Below 25 is the washed-out line on this report’s scale, and this is the first time it has been crossed since these reports started. Fewer than one in four S&P 500 stocks hold their 50-day average while the index sits half a percent from its own.
The long-horizon readings kept sliding. S5TH is at 42.54, two and a half points above the 40 line. MMTH is at 43.23. Both are lower than a week ago.
Friday was different. MMTW jumped 17% in one session to 30.70, which puts it back above its own average for the first time in weeks. MMFI rose 11%, and new highs versus new lows went from 0.09x to 0.34x. That’s a real bounce off the lows. It isn’t yet a turn: every one of those readings is still in contraction, and new lows still outnumber new highs three to one.
The concentration gap flipped negative on the 200-day horizon too, −0.69 on top of −3.23 on the 50-day. S&P 500 breadth is now weaker than broad-market breadth on both measures. Large-cap index members have been falling faster than the market around them, while a small group at the very top keeps the index up.
Washed out is a level, not a signal. It tells you selling has gone far. It doesn’t tell you it’s over. The readings that would say that are MMTW back above 50 and new highs outnumbering new lows, and neither is close.
───────────────────────────────────────────
WHAT MACRO SAYS
───────────────────────────────────────────
The 10-year closed at 5.275%, another nineteen-year high and up about eleven basis points on the week. The detail that matters is Friday. Payrolls came in at 29,000 against roughly 90,000 expected, unemployment rose to 4.2%, and October hike odds collapsed from about two in three to roughly one in six. The 10-year dipped toward 5.17% on the release, then reversed and finished the day higher.
A weak jobs report usually pulls long yields down. This one didn’t, and the reason is in Thursday’s ISM: factory prices paid jumped nearly seven points to 77.9. The bond market isn’t pricing the Fed anymore. It’s pricing inflation that doesn’t need the Fed’s help.
VIX closed at 15.30, below all four of its own averages. Same reading, same interpretation as the last three weeks: an absence of hedging, not a presence of safety.
───────────────────────────────────────────
WHAT ROTATION SAYS
───────────────────────────────────────────
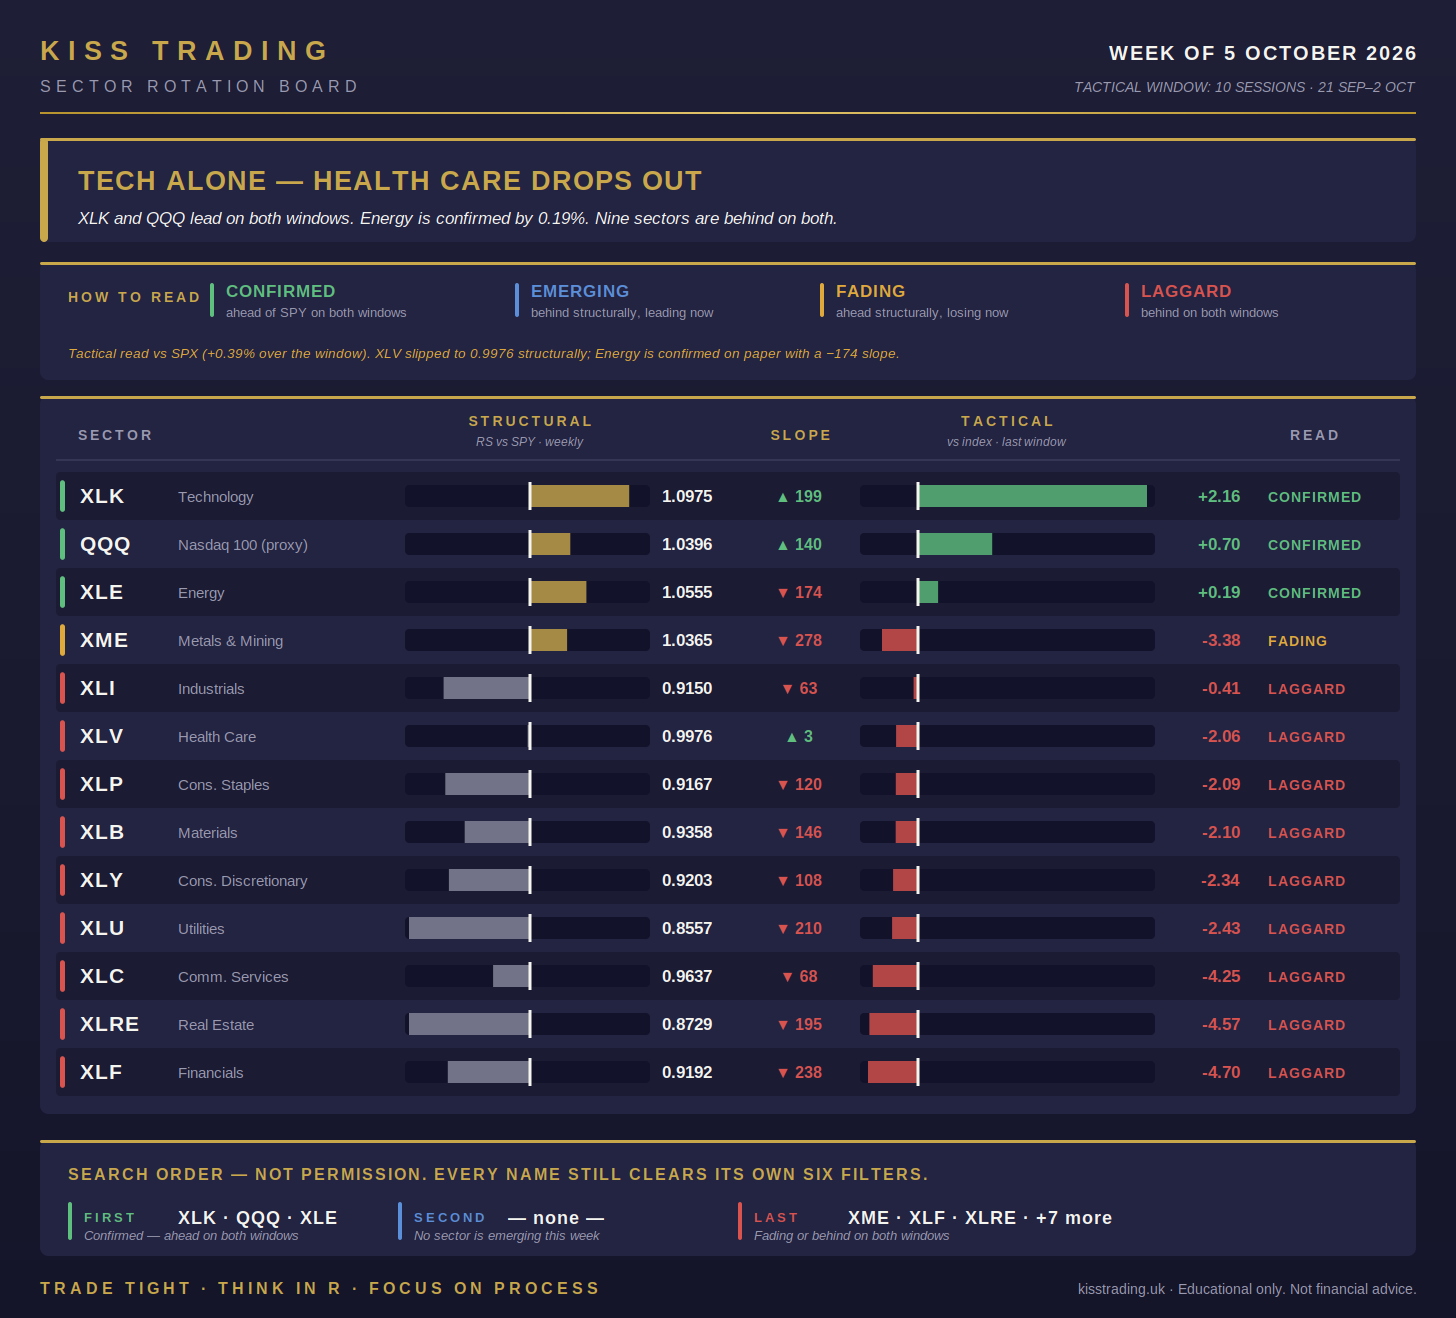
Technology is the market. XLK is ahead of SPY structurally at 1.0975, ahead tactically by 2.16%, and accelerating at +199 a week — the strongest slope on the board by a wide margin. QQQ is confirmed alongside it.
Health Care dropped out. A week ago XLV was confirmed on structure; this week it slipped to 0.9976 and lost 2.06% against the index over the window. It’s now behind on both windows. That matters for anyone who has been looking at health-care breakouts: the sector context underneath them is gone.
Energy is confirmed on paper. Structural RS at 1.0555, tactically ahead by 0.19% — but its weekly slope is −174, the third-worst deceleration on the board. That’s a sector still ahead of SPY on the numbers while losing ground every week. Confirmed by the rule, fading in motion.
Nine sectors are behind on both windows. Financials (−4.70%), Real Estate (−4.57%) and Comm. Services (−4.25%) lead the losses; the rate-sensitive groups keep reacting to a 5.3% ten-year exactly as you’d expect.
Two names lead and one is hanging on. That isn’t rotation. It’s the same concentration the breadth panel shows, seen from the sector side.
Search order is search order, not permission. Expect most Tech names to fail the ceiling test: a sector up 2% against the index in ten sessions, on top of the run before it, rarely leaves a tight base.
───────────────────────────────────────────
MACRO — WHAT LAST WEEK DELIVERED
───────────────────────────────────────────
→ PCE (August), Wednesday: headline +0.3% monthly and 3.4% annual, below the 0.4% expected. Core +0.2% monthly, 3.0% annual — lighter than forecast. Real spending +0.6%.
→ ISM Manufacturing (September), Thursday: 54.5 vs 55.0 expected. Prices paid 77.9 vs 72.3 expected, up 6.8 points. New orders 55.3, employment 52.7.
→ Nonfarm Payrolls (September), Friday: +29,000 vs about +90,000 expected. Unemployment 4.2%. Hourly earnings +0.1% monthly, 3.0% annual. July and August revised down by a combined 60,000.
→ Oil: Brent around $102, WTI around $91, both roughly flat on the week. G7 announced a release of up to 100 million barrels from reserves over four months. Middle East exports are recovering toward pre-war levels; US–Iran negotiations continue, alongside reports of additional US military deployments to the region.
Fed funds: 3.75%–4.00%. October hike odds fell from about 66% to roughly 15% after payrolls. Chicago Fed President Goolsbee said inflation remains the more pressing part of the mandate.
───────────────────────────────────────────
MACRO FLAGS — WEEK AHEAD
───────────────────────────────────────────
→ Sunday 4 October: OPEC+ meeting, output targets expected unchanged
→ Monday 5 October, 10:00 ET: ISM Services (September). Watch the prices index, not the headline.
→ Wednesday 7 October, 14:00 ET: FOMC Minutes from the September hike
→ Wednesday 14 October: September CPI — the week after next
Calendar note: no CPI, FOMC decision or payrolls this week, so every arming evening is clean. Looking one week ahead, CPI on Wednesday 14 October makes that a no-new-order session; the last clean arming evening before it is Monday 12 October. Third-quarter earnings season starts in mid-October, so check every candidate’s report date against the hold rule before arming.
───────────────────────────────────────────
VERDICT RATIONALE
───────────────────────────────────────────
NEUTRAL holds, and it holds for the same reason it was granted: SPY is above its 20 SMA and both indices confirm Stage 2. Nothing in that test changed this week.
What changed sits around it. Breadth reached washed-out levels. The 10-year made a new high on news that should have lowered it. Health Care left the leadership group. None of those is one of the four conditions, so none of them moves the verdict. That’s deliberate. Breadth is recorded, never a gate; rotation is context, never a filter. A regime call that shifts every time a secondary reading looks bad isn’t a rule, it’s a mood.
What it does change is the practical posture. NEUTRAL permits selective entries. In a market this narrow, “selective” means very few, and the ones that qualify will mostly come from one sector.
What upgrades this to BULLISH CAUTION: MMTW back above 50 and holding, or new highs outnumbering new lows. Friday was the first step in that direction. One session isn’t a trend.
What takes it back to BEARISH: a SPY close below its 20 SMA at 764.83 — 0.62% below Friday’s close, the closest the trigger has been since the upgrade.
The four conditions, as they stand:
→ SPY closed below its 20 SMA — CLEARED, 769.64 vs 764.83
→ Broad short-term breadth under 50 — FIRED, MMTW at 30.70
→ US 10-year above 4.75% decisively — FIRED, 5.275%, a new nineteen-year high
→ A Middle East supply headline moving oil sharply higher — FIRED, Brent near $102 with Hormuz unresolved, though exports are recovering and the G7 reserve release is the second de-escalating input in two weeks
═══════════════════════════════════════════
WATCHLIST + TRADE PLAN (PAID)
═══════════════════════════════════════════
Paid subscribers receive immediately below:
→ The Weekly Watchlist — every name scanned, every name
rejected, and the exact number that killed each one
→ Entry triggers, Retest Shield levels, and R-targets
→ The Trade Plan of the Week — fully sized, ready to execute
Everything is decided before Monday opens. You execute.
The system does the thinking.
Upgrade at kisstrading.uk to access the full system.
───────────────────────────────────────────
Trade Tight · Think in R · Focus on Process
— Radu
KISS Trading
───────────────────────────────────────────
⚠️ Educational only. Not financial advice. Always DYOR.