
═══════════════════════════════════════════
WEEKLY REGIME VERDICT
═══════════════════════════════════════════
NEUTRAL
Posture: 30–50% capital — cleanest setups only
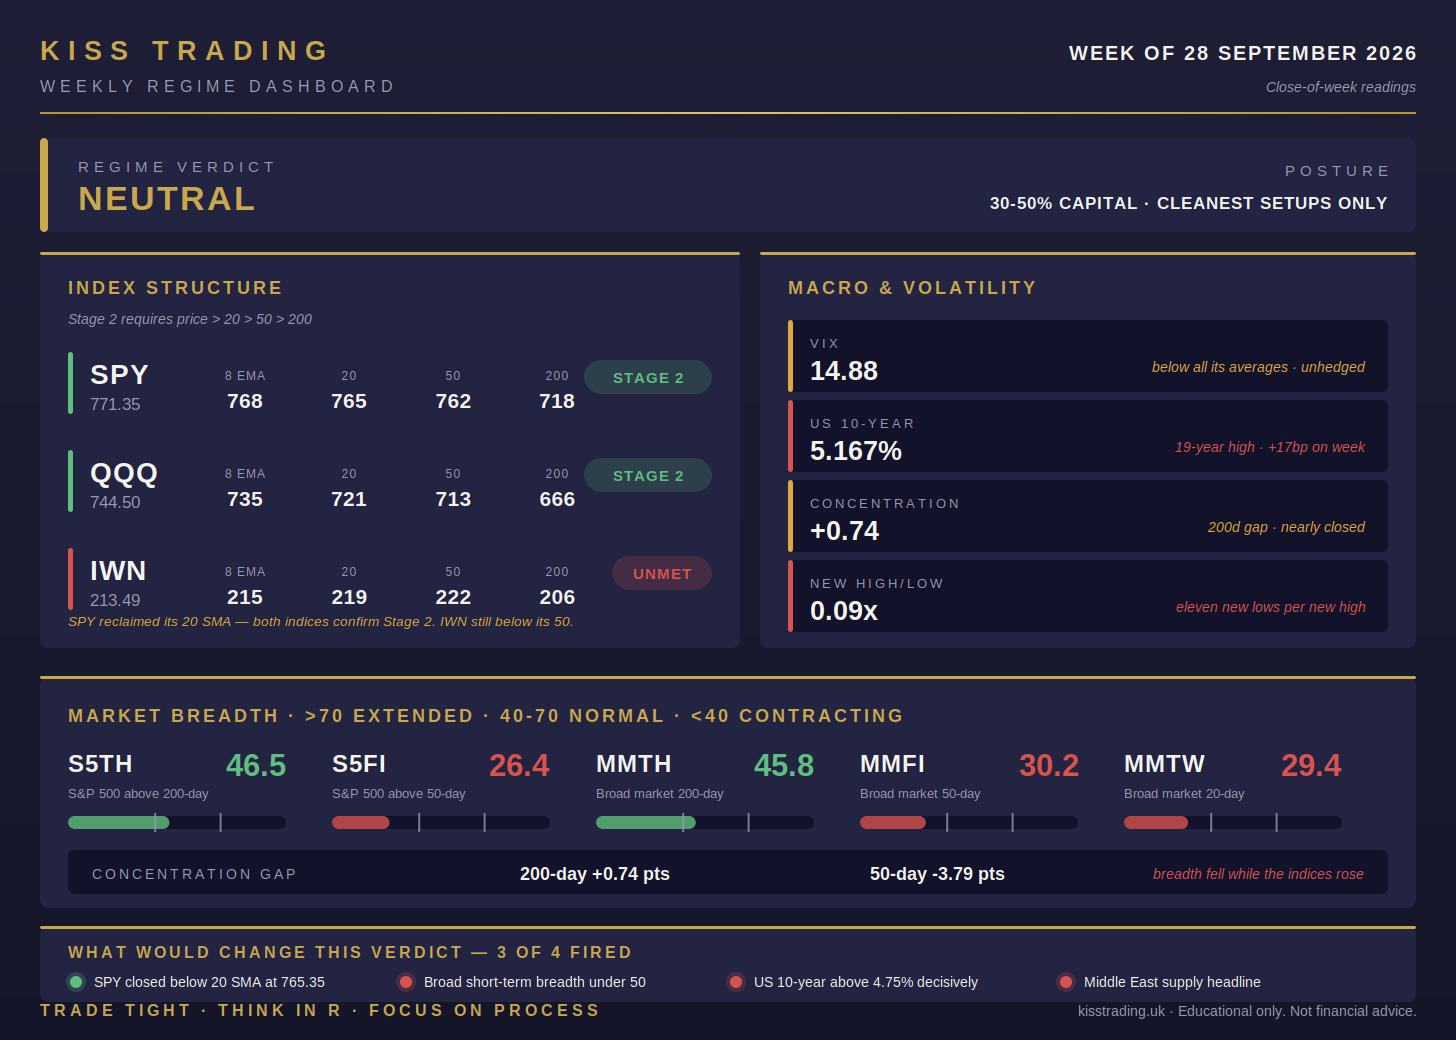
Upgraded from BEARISH. SPY closed back above its 20 SMA, and both indices now confirm Stage 2.
Last week’s report named the exact trigger for this upgrade: a SPY daily close above its 20 SMA with QQQ holding Stage 2. It happened. So the verdict moves, and it moves without a debate — the same way it moved down two weeks ago.
What follows is the uncomfortable part, because almost nothing else improved.
───────────────────────────────────────────
WHAT THE STRUCTURE SAYS
───────────────────────────────────────────
SPY closed at 771.35, above the 8 EMA at 767.63, the 20 SMA at 765.35, the 50 at 761.57 and the 200 at 718.45. The stack is ordered and rising. A week ago price was under the 20 and the lines were stacked flat on top of each other.
QQQ is stronger still, at 744.50 against a 20 SMA at 720.87. It gained 3.2% on the week while SPY gained 1.3%. That’s the whole market in two numbers.
IWN didn’t come along. At 213.49 it’s below the 8 EMA at 215.22, the 20 SMA at 218.80 and the 50 at 221.90, and it fell about 1% on a week when both large-cap indices rose. Small-cap value has now lagged for four straight weeks.
Key levels for the week:
→ SPY support: 765.35 (20 SMA), then 761.57 (50 SMA) · resistance: 772.28, Friday’s high
→ QQQ support: 734.75 (8 EMA), then 720.87 (20 SMA) · resistance: none, at new highs
───────────────────────────────────────────
WHAT BREADTH SAYS
───────────────────────────────────────────
Four of five readings fell in a week when the S&P 500 rose. That’s the sentence to sit with.
S5TH is at 46.52, down from 49.50. MMTH at 45.78, down from 47.95. S5FI at 26.44, MMFI at 30.23, both lower again. Only MMTW improved, to 29.44 from 26.82, and it’s still deep in contraction. Roughly seven in ten stocks are below their own 20-day average while the index sits near its highs.
New highs versus new lows is the reading that should stop you. It fell to 0.09x from 0.20x. That’s eleven stocks making new lows for every one making a new high, in a rising market. This system has never recorded a number that low.
The concentration gap keeps compressing — 200-day at +0.74, 50-day at −3.79 — but for the wrong reason again. It isn’t that the broad market is catching up. It’s that the S&P 500’s own members are falling toward everyone else while a handful of large names carry the index.
Breadth is recorded here, never a gate. It doesn’t veto the verdict and it doesn’t size a position. What it does is tell you what the scan will find: in a market with eleven new lows per new high, most charts that look like a base are a stock that stopped falling, not a stock being accumulated.
───────────────────────────────────────────
WHAT MACRO SAYS
───────────────────────────────────────────
The 10-year closed at 5.167%, with an intraday high of 5.228%. That’s up about 17 basis points on the week and the highest level in roughly nineteen years. October hike odds sit at 66% on CME FedWatch. The bond market has moved from pricing one hike to pricing a sequence.
So far equities have absorbed it. The climb has been orderly rather than violent, and an orderly rise in yields is something a market can digest. A gap higher is not.
VIX closed at 14.88, below all four of its own averages, in a week when the 10-year hit a nineteen-year high and most stocks fell. Same reading as last week and the same interpretation: not safety, just an absence of hedging.
Oil finally broke. WTI fell about 9% on the week to roughly $92, while Brent held near $104 and finished close to flat. That gap between the two is the Hormuz premium, still sitting on the seaborne barrel.
───────────────────────────────────────────
WHAT ROTATION SAYS
───────────────────────────────────────────
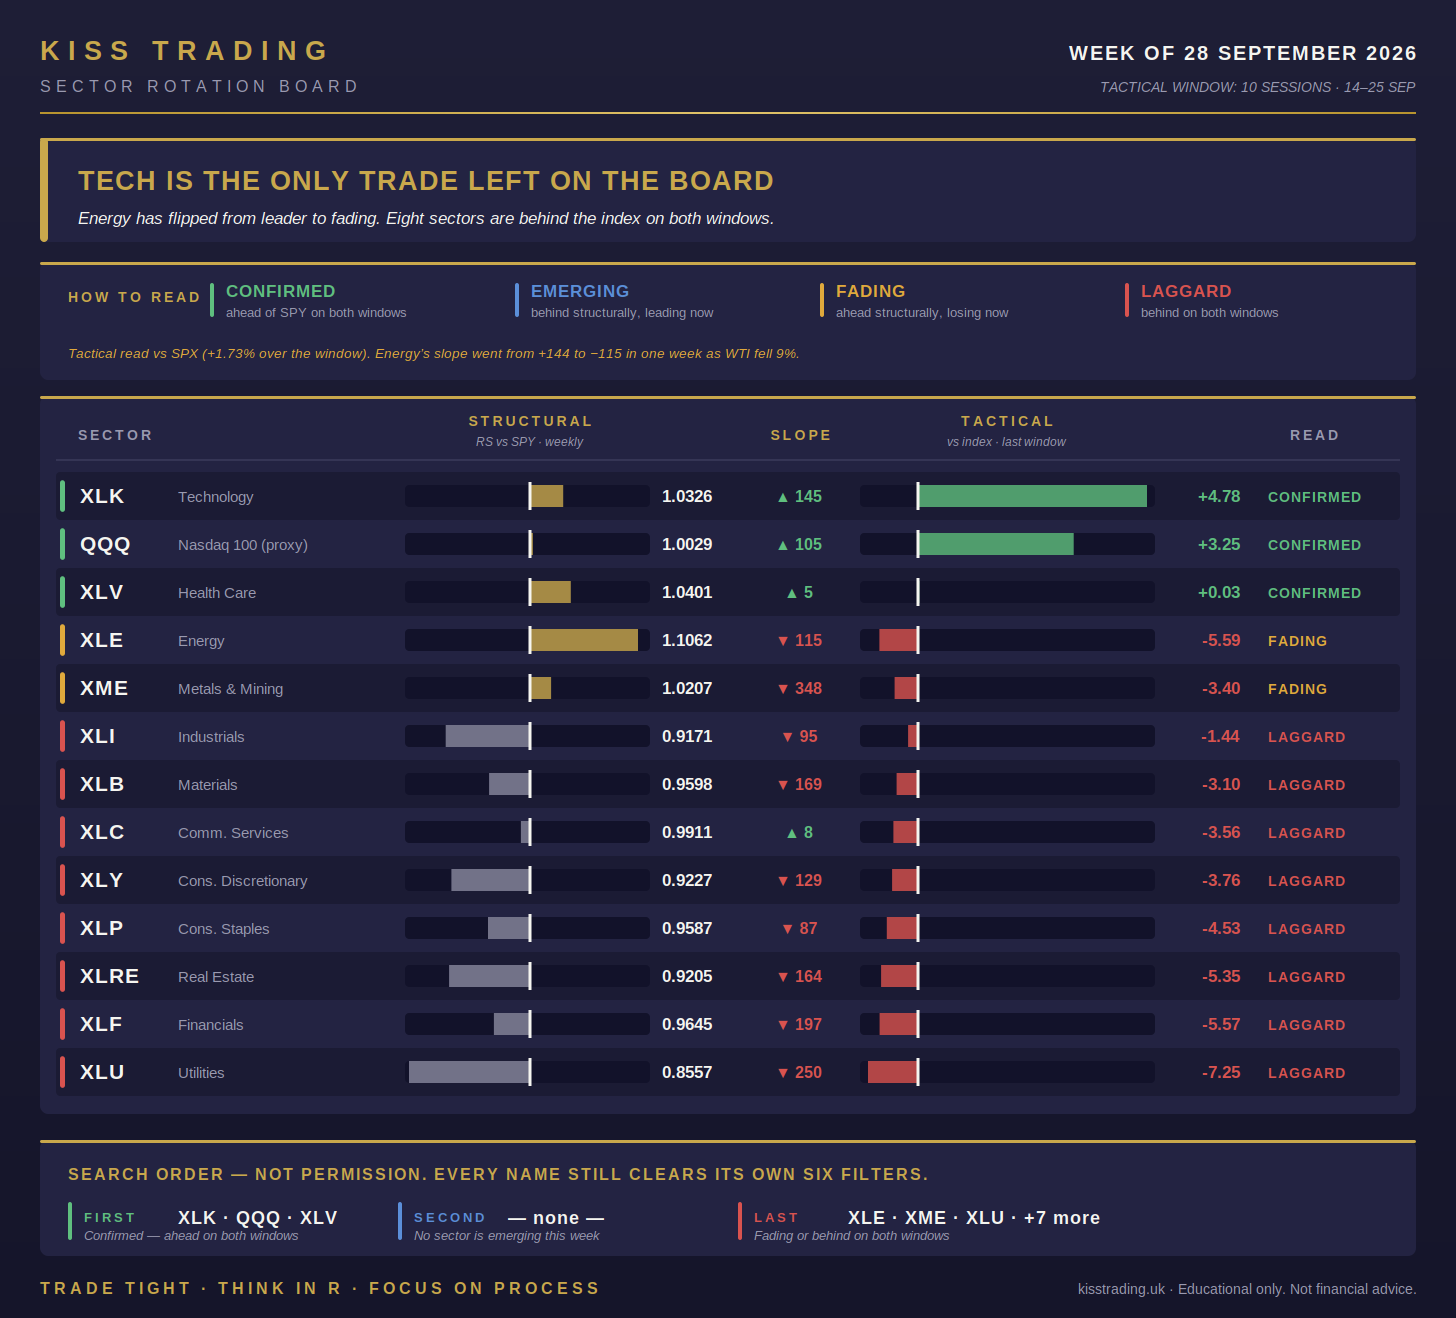
The big change is Energy. Last week XLE was the strongest structural leader on the board and accelerating at +144 a week. This week it’s still ahead structurally at 1.1062, but it lost 5.59% against the index over the window and its slope has flipped to −115. That’s a leader coming apart in real time, and it’s the oil move showing up in the tape.
Metals & Mining is doing the same thing, at −348 a week, the worst deceleration on the board for a second week running.
Technology is now the market. XLK is ahead structurally at 1.0326, ahead tactically by 4.78%, and accelerating at +145. QQQ joins it as confirmed. Health Care stays confirmed on structure at 1.0401, but its tactical edge is +0.03% — that’s a tie, not a lead, and its slope has flattened to +5.
Eight sectors are behind the index on both windows. Utilities is the worst at −7.25% tactically, Financials at −5.57%, Real Estate at −5.35%. Those are the rate-sensitive groups and they’re reacting exactly as you’d expect to a 5.17% ten-year.
Read the whole board and it says one thing: this is not a market that rotated, it’s a market that narrowed. Capital didn’t move from one sector to another. It concentrated into one.
The search order at the bottom of that board is an order to search in, not permission. Expect to look at Tech first and find most names extended past the dynamic ceiling. A sector up nearly 5% against the index in ten sessions rarely leaves a tight base underneath it.
───────────────────────────────────────────
MACRO — WHAT LAST WEEK DELIVERED
───────────────────────────────────────────
→ Xi state visit to Washington, Wednesday to Friday. The 11-month trade truce was extended through 10 January 2027. Also agreed: a Board of Trade and Investment, Boeing aircraft orders and US agricultural purchases.
→ US–Iran talks in New York, exploring a phased path out of the war — Tehran reopening the Strait of Hormuz in exchange for Washington lifting its economic blockade. Hormuz flows ran at 33.7 million barrels in the week of 20 September.
→ Oil, all week: WTI down about 9% to roughly $92. Brent near $104, roughly flat, as Houthi strikes on Saudi infrastructure continued.
→ Rates: 10-year at 5.167%, intraday 5.228%. October hike odds at 66%.
Fed funds: 3.75%–4.00%. Fed speakers spent the week pointing at strong data, which is now a problem for bonds rather than a comfort: good data means more hikes.
───────────────────────────────────────────
THE SUMMIT — WHAT IT ACTUALLY CHANGED
───────────────────────────────────────────
Worth a section of its own, because it’s the kind of event that gets over-traded in both directions.
What was delivered is real but narrow: a truce extension to 10 January, purchase commitments, and a framework to keep talking. Rare earths were on the agenda. Taiwan was on the agenda, with a $14 billion US arms package still on hold. So was a notification mechanism for AI incidents affecting national security.
What that does for a swing trader is remove a cliff, not create a trend. There was a tariff deadline sitting in the calendar and it has moved to January. Removing a known date doesn’t start an uptrend; it takes one source of gap risk off the board for three months.
The honest read on the price action: Tech was already leading before the summit, and the week’s gains were concentrated in the same chip and AI names that have been leading since the Fed hiked. Attributing that move to the summit is a story told backwards. If you want a summit trade, the cleanest expression would be rare-earth and industrial names on an actual export agreement — and there isn’t one yet, only an agenda item.
The part to watch is January. A truce with an expiry date is a scheduled event, and this system already has a rule for scheduled events: no new orders into them.
───────────────────────────────────────────
MACRO FLAGS — WEEK AHEAD
───────────────────────────────────────────
→ Tuesday 29 September, 10:00 ET: JOLTS (August)
→ Wednesday 30 September, 08:30 ET: PCE (August) and Q2 GDP third estimate. Quarter-end.
→ Thursday 1 October, 08:30 ET: jobless claims. 10:00 ET: ISM Manufacturing
→ Friday 2 October, 08:30 ET: September employment report
Calendar note: payrolls Friday makes that a no-new-order session, so the last clean arming evening this week is Wednesday, for Thursday’s open — not Thursday. PCE on Wednesday isn’t on the blocked list, but it lands the same morning as quarter-end rebalancing, so treat Wednesday’s volume readings with some suspicion at 15:45.
───────────────────────────────────────────
VERDICT RATIONALE
───────────────────────────────────────────
NEUTRAL, and it’s worth explaining why the upgrade is automatic when the evidence underneath it got worse.
The conditions were published in advance and one of them cleared. SPY is back above its 20 SMA, both indices confirm Stage 2, and the trigger for this upgrade was printed in last week’s report before it happened. Refusing to honour it because breadth looks awful would be the same error as ignoring a downgrade because the tape felt fine — just pointed in the friendlier direction. A rule you only follow when you agree with it isn’t a rule.
What NEUTRAL means in practice is narrow, not enthusiastic. Capital deployment is 30–50%, cleanest setups only. Three of four conditions are still firing. Breadth is the weakest this report has recorded. Expect the scan to reject most of what it looks at, and expect the rejections to cluster in the ceiling test, because the only sector leading has already run.
What upgrades this to BULLISH CAUTION: MMTW back above 50 and holding, or new highs outnumbering new lows again. Either would mean participation is broadening rather than concentrating. Neither is close.
What takes it back to BEARISH: a SPY close below its 20 SMA at 765.35, which is 0.76% below Friday’s close.
The four conditions, as they stand:
→ SPY closed below its 20 SMA — CLEARED, 771.35 vs 765.35
→ Broad short-term breadth under 50 — FIRED, MMTW at 29.44
→ US 10-year above 4.75% decisively — FIRED, 5.167%, a nineteen-year high
→ A Middle East supply headline moving oil sharply higher — FIRED, Brent near $104 with Hormuz unresolved, though the New York talks are the first genuine de-escalation path since this condition was written
═══════════════════════════════════════════
WATCHLIST + TRADE PLAN (PAID)
═══════════════════════════════════════════
Both return this week, for the first time in three weeks.
Paid subscribers receive immediately below:
→ The Weekly Watchlist — every name scanned, every name
rejected, and the exact number that killed each one
→ Entry triggers, Retest Shield levels, and R-targets
→ The Trade Plan of the Week — fully sized, ready to execute
Everything is decided before Monday opens. You execute.
The system does the thinking.
Upgrade at kisstrading.uk to access the full system.
───────────────────────────────────────────
Trade Tight · Think in R · Focus on Process
— Radu
KISS Trading
───────────────────────────────────────────
⚠️ Educational only. Not financial advice. Always DYOR.