
═══════════════════════════════════════════
WEEKLY REGIME VERDICT
═══════════════════════════════════════════
BEARISH
Posture: no new entries — cash and existing positions only
Held for a third week. SPY is still below its 20 SMA, QQQ is still below its 50, and all four conditions are still firing — one of them by less than a fifth of a point.
This was the week breadth came back and the index didn’t. More than half of the S&P 500 is above its 50-day average again. The index itself finished lower. When those two disagree, this report goes with the index — because the index is where the conditions live.
───────────────────────────────────────────
WHAT THE STRUCTURE SAYS
───────────────────────────────────────────
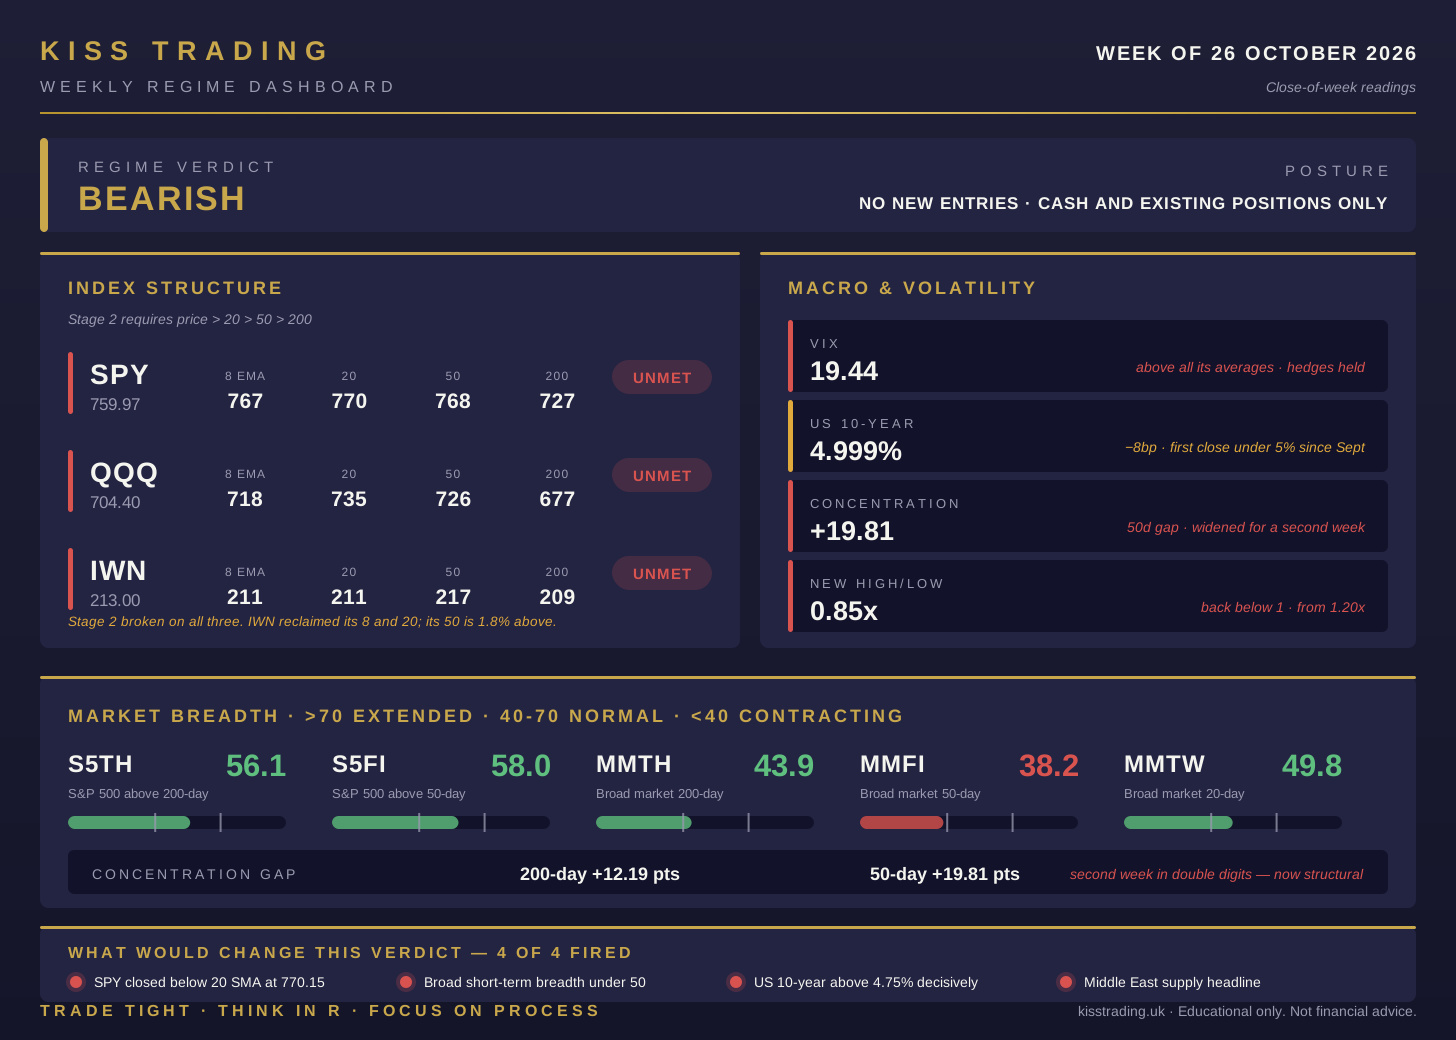
SPY finished slightly lower on the week and never got back to its 20 SMA. The 8 EMA, the 20 and the 50 now sit in a three-point band above price, and the closer they bunch, the more weight the first close through them will carry — in either direction.
QQQ is the reason Thursday hurt. The Nasdaq fell 2.6% in one session after Meta raised its spending floor, and QQQ ended the week 4.4% below its 20 SMA. Its 8 EMA is now below both the 20 and the 50.
IWN did the opposite. It rose 2% on the week and reclaimed its 8 EMA and 20 SMA. Its 50 SMA is still 1.8% overhead and falling, so the badge stays UNMET. It’s the first index to move in the right direction since the regime turned.
Key levels for the week:
→ SPY: 770.15 (20 SMA) is the level that matters, 1.3% above Friday’s close · support at the 200 SMA, 727.01
→ QQQ: 735.24 (20 SMA) is 4.4% away · support at the 200 SMA, 677.30
───────────────────────────────────────────
WHAT BREADTH SAYS
───────────────────────────────────────────
Every bar on the board rose. S5FI went from 45 to 58, back above 50 for the first time since early September. MMFI rose ten points, and MMTW from 40 to 49.84. That’s one good Friday short of clearing condition 2, and Friday wasn’t good: every breadth series dropped more than 2% on the day.
The broadening is real, but look at where it came from. The S&P members rose much faster than the broad market. The concentration gap widened to +12.19 on the 200-day row and +19.81 on the 50-day. That’s the second week in double digits on both horizons. The specification calls a gap that persists structural, not noise. It has now persisted.
New highs fell back under new lows, 0.85x. Last week’s 1.20x was the defensive sectors setting records. This week they held, but nothing new joined them.
───────────────────────────────────────────
WHAT MACRO SAYS
───────────────────────────────────────────
The 10-year closed at 4.999%, its first close under 5% since September, and down for a second week. Direction keeps improving. Level doesn’t count until 4.75%, and it’s still a quarter-point above.
VIX barely moved and stayed above every average. The hedges bought in mid-October haven’t been taken off. That is the opposite of the complacency we flagged in September.
Oil did the most work. WTI rose 4% on Thursday to around $105, and Brent traded above $110. October has now seen more attacks on commercial shipping around the Gulf than any month since the war began. Condition 4 isn’t close to clearing.
───────────────────────────────────────────
WHAT ROTATION SAYS
───────────────────────────────────────────
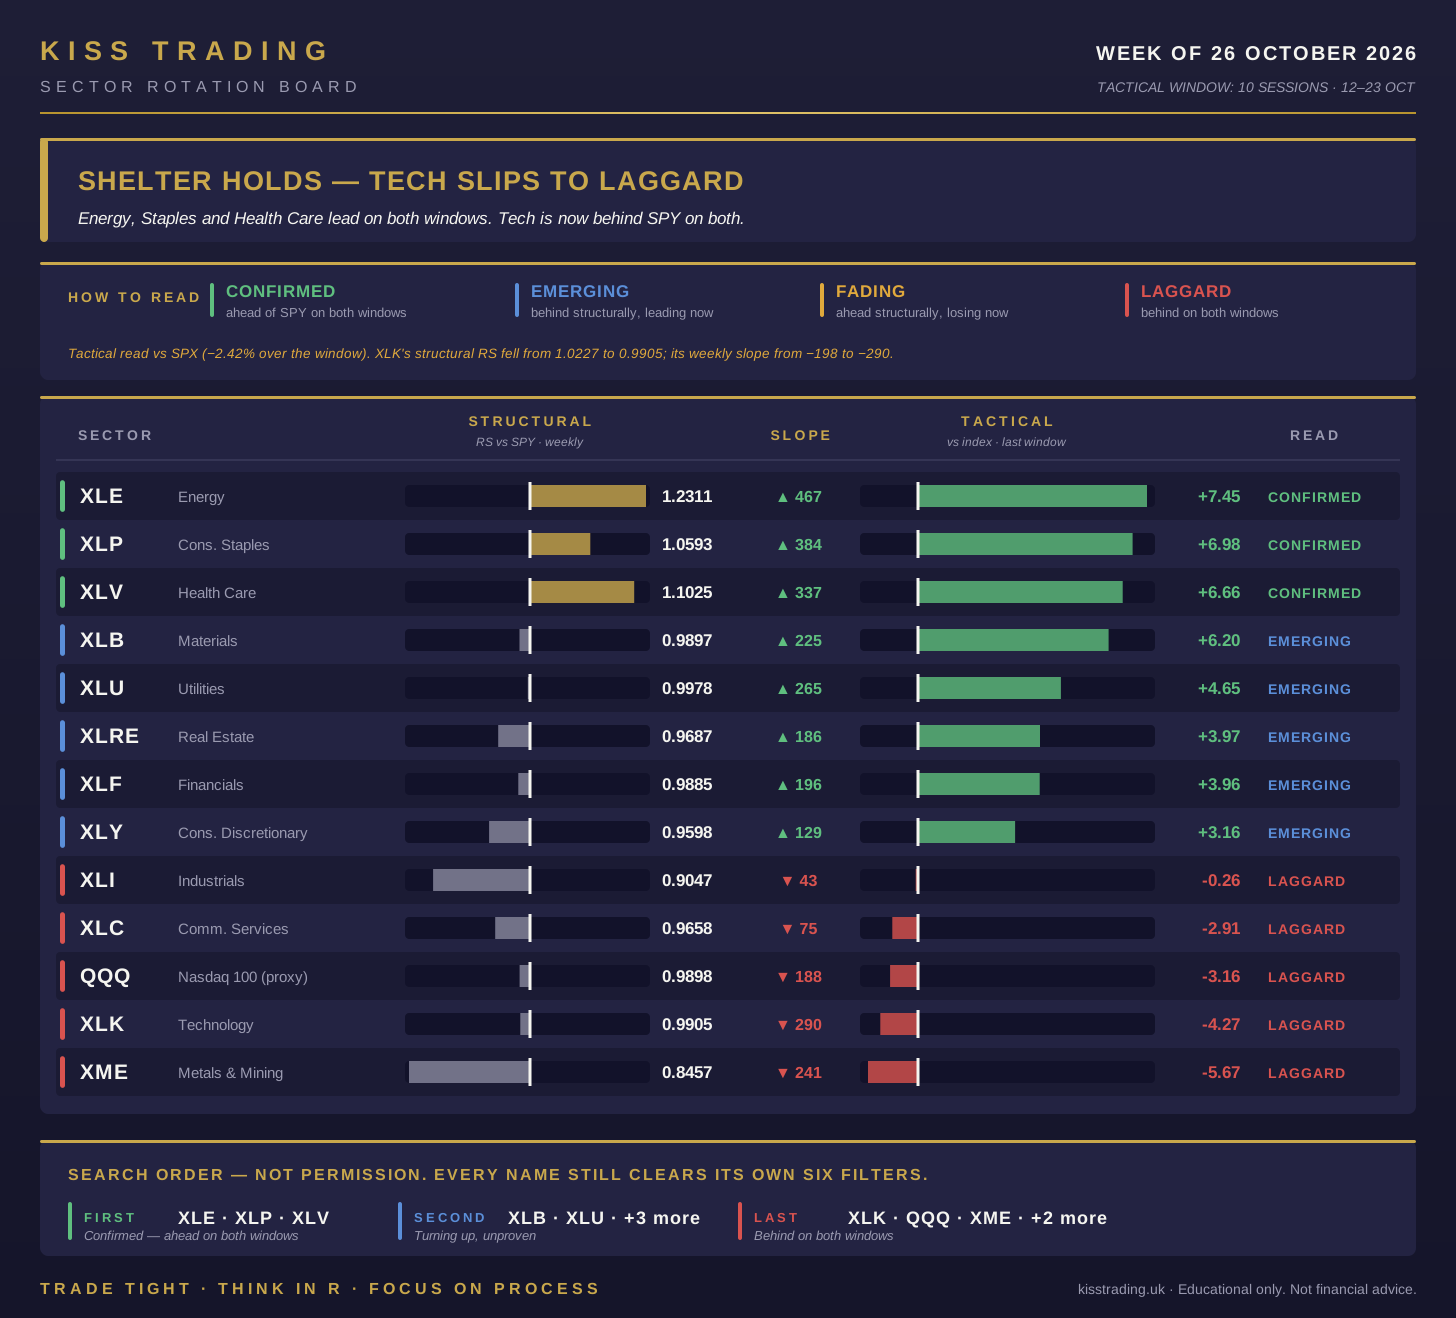
The same three confirmed sectors as last week: Energy, Staples, Health Care. Energy leads both windows, at 1.23 against SPY structurally and +7.45% tactically, with the steepest slope on the board. Staples and Health Care follow within a point.
Behind them, five sectors are emerging, all above the index over ten sessions while still behind it structurally. Materials is the strongest at +6.20%, then Utilities, Real Estate, Financials and Discretionary.
Technology moved from FADING to LAGGARD. A week ago XLK was still ahead of SPY on the structural window; now it’s at 0.9905, behind on both. Its weekly slope fell again, from −198 to −290, the weakest on the board. QQQ, Communication Services, Metals and Mining, and Industrials sit with it.
Two weeks ago Technology was the only confirmed sector. Since then, every sector that can lead in a strong economy has fallen behind, and every sector that leads in a defensive one has moved ahead. That’s not rotation inside a bull market. It’s capital looking for shelter.
───────────────────────────────────────────
MACRO — WHAT LAST WEEK DELIVERED
───────────────────────────────────────────
→ Meta, Wednesday after the close: revenue beat, but the lower end of its capex forecast rose to $135–145 billion. The stock fell sharply Thursday and took the Nasdaq down 2.6% with it.
→ Tesla, Wednesday after the close: shares fell after the results.
→ AI financing: Morgan Stanley cut its CoreWeave target, citing financing uncertainty — the same thread that broke semiconductors two weeks ago.
→ S&P Global flash PMI (October), Friday: composite 57.6, down from 58.4. New orders at 58.2, the strongest since March 2022. Output prices at 59.8, the highest since August 2022.
→ University of Michigan sentiment (final October), Friday: 48.0. One-year inflation expectations 4.7%.
→ Oil: WTI near $105 after a 4% jump Thursday. Brent above $110. The Strait of Hormuz remains effectively closed to commercial traffic.
→ US 10-year: from about 5.08% to 5.00%. Gold fell about 4% to near $4,000.
→ Indices: S&P 500 down about 0.3% on the week. Thursday was the damage: S&P −1.2%, Nasdaq −2.6%.
───────────────────────────────────────────
MACRO FLAGS — WEEK AHEAD
───────────────────────────────────────────
→ Tuesday 27 October: Durable goods (September)
→ Wednesday 28 October: FOMC decision. A hold at 3.75–4.00% is expected after September’s hike. The market will watch for a tightening bias toward December and for dissents from the members who wanted a hike in July.
→ Thursday 29 October: Q3 GDP, advance estimate. Consensus around 3.0%; the Atlanta Fed’s model shows 3.5%.
→ Thursday 29 October: PCE (September). Headline expected +0.5% m/m, 3.6% y/y. Core +0.3% m/m, 3.1% y/y.
→ Same week: the Bank of Canada, ECB and Bank of Japan also decide.
Calendar note: Wednesday is an FOMC session, which makes it a no-new-order day, and Tuesday evening is not an arming evening. In a BEARISH regime that changes nothing — no orders are armed on any evening. If the regime is restored next Sunday, the calendar for the week of 2 November is checked fresh.
───────────────────────────────────────────
VERDICT RATIONALE
───────────────────────────────────────────
BEARISH holds because nothing in last week’s restoration test moved. SPY needed a close above its 20 SMA. It got closer, then fell back. QQQ needed the same and finished further away than it started.
Breadth improved more this week than in any week since the regime turned. That improvement is real, and it is recorded on the dashboard. It does not move the verdict. Breadth is recorded, never a gate. A market where 58% of large caps are above their 50-day average but the index is below its own 20-day is a market where the money left the stocks that carry the index. That’s not a recovery. It’s a reallocation.
Condition 2 is the one to watch. MMTW at 49.84 is 0.16 from clearing. A close above 50 would make it the first condition to clear since mid-October. It would not, on its own, restore NEUTRAL.
What restores NEUTRAL: a SPY close above its 20 SMA at 770.15, together with QQQ back in Stage 2, which requires a close above its 20 SMA at 735.24. SPY is 1.3% away. QQQ is 4.4% away.
What would make it worse: SPY losing its 200 SMA at 727.01, 4.3% below Friday’s close.
The four conditions, as they stand:
→ SPY closed below its 20 SMA — FIRED, 759.97 vs 770.15
→ Broad short-term breadth under 50 — FIRED, MMTW at 49.84
→ US 10-year above 4.75% decisively — FIRED, 4.999%, falling for a second week
→ A Middle East supply headline moving oil sharply higher — FIRED, Brent above $110 after the heaviest month of shipping attacks since the war began
═══════════════════════════════════════════
WHY THERE IS NO WATCHLIST THIS WEEK
═══════════════════════════════════════════
Paid subscribers will not receive a Watchlist or a Trade Plan this Sunday. This is the second week in a row, for the same reason.
A BEARISH verdict means no new entries. The scan keeps running in the background. The names holding their structure through this are the ones that will lead the list when the regime turns, and this week’s breadth surge says there are more of them than a week ago.
It’s tempting to read a week like this as the turn. Breadth jumped, yields fell, small caps reclaimed their short averages. But the index — the thing the conditions are written around — closed lower. The system doesn’t predict the turn. It waits for the close that proves it.
Cash is a position. For one more week, it’s the only one the system allows.
───────────────────────────────────────────
Trade Tight · Think in R · Focus on Process
— Radu
KISS Trading
───────────────────────────────────────────
⚠️ Educational only. Not financial advice. Always DYOR.