
═══════════════════════════════════════════
WEEKLY REGIME VERDICT
═══════════════════════════════════════════
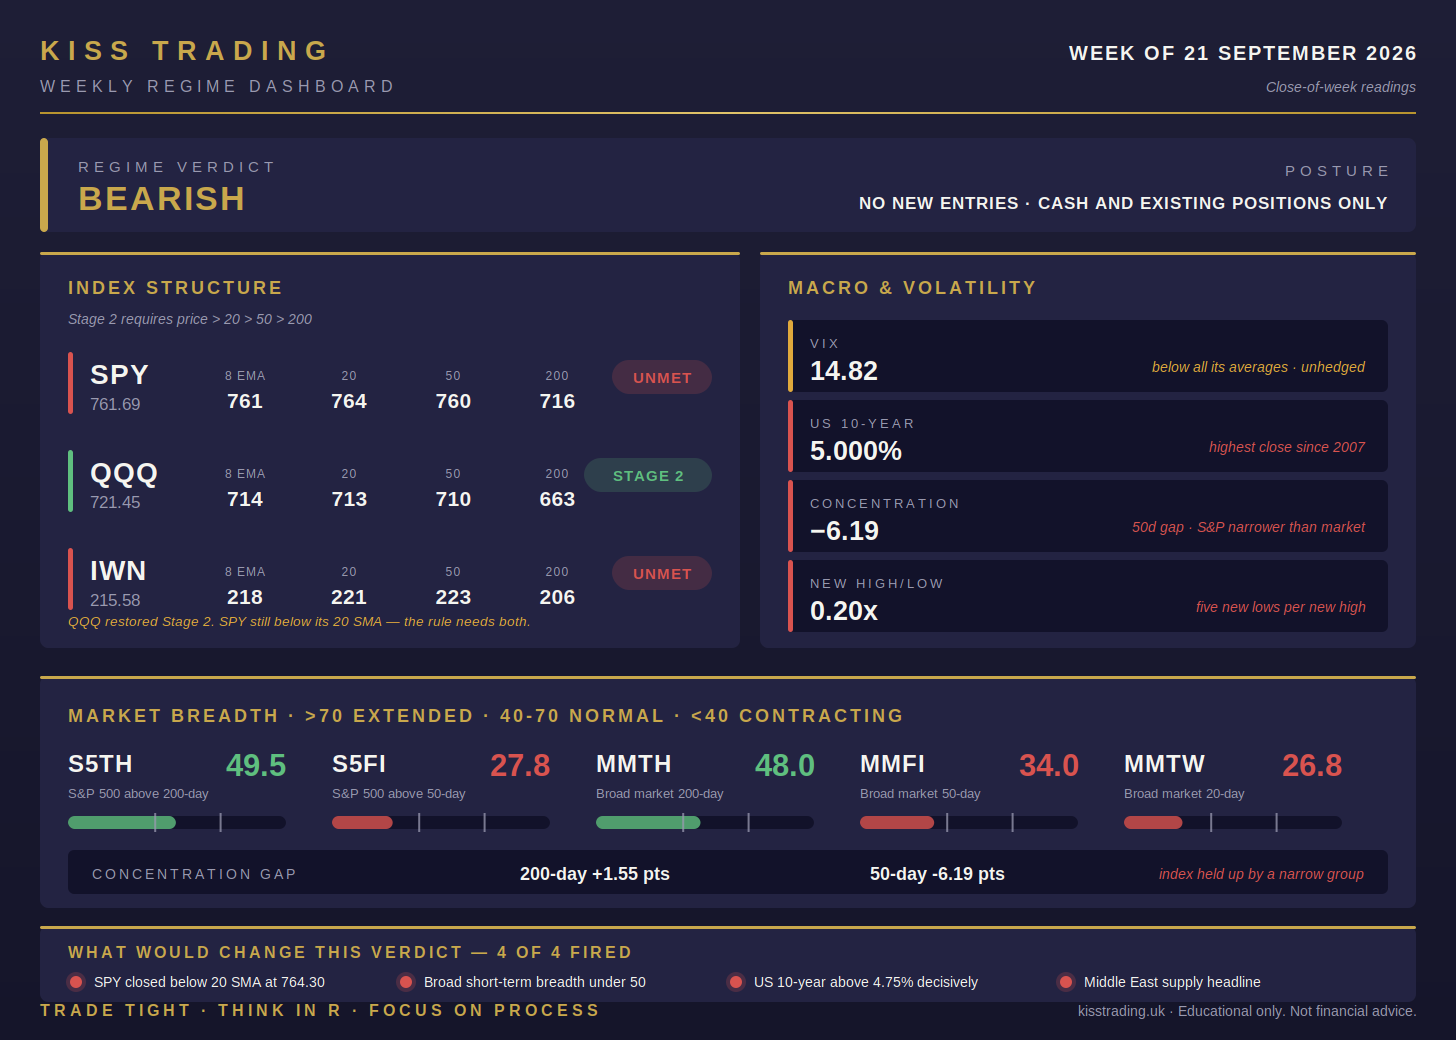
BEARISH
Posture: no new entries. Cash and existing positions only.
Held from last week. All four invalidation conditions are still firing, and SPY is still below its 20 SMA.
On paper, this was a quiet week. The S&P 500 finished down about 0.1%, Nasdaq was up 0.7%, and QQQ repaired its structure. Underneath, the market got clearly worse. Everything below is about that gap.
───────────────────────────────────────────
WHAT THE STRUCTURE SAYS
───────────────────────────────────────────
SPY closed at 761.69, below its 20 SMA at 764.30. It sits just above the 8 EMA at 761.12 and the 50 SMA at 759.73, so all three lines are within about half a percent of price. That’s a stack squeezed flat, not an ordered one. Stage 2 is still unmet.
QQQ is the one real change. It closed at 721.45, above the 8 EMA at 713.65, the 20 SMA at 713.24, the 50 at 709.95 and the 200 at 662.60. The stack is back in order and Stage 2 is restored. A week ago it was broken.
That doesn’t change the verdict. Chapter 2 asks for both indices, not either one. One index repairing while the other stays broken is divergence, not confirmation.
IWN is still the weakest of the three. At 215.58 it’s below the 8 EMA at 218.00, the 20 SMA at 221.30 and the 50 SMA at 222.55, and the 20 has crossed under the 50. Only the 200-day at 205.55 is holding it up.
Key levels for the week:
→ SPY support: 759.73 (50 SMA), then Wednesday’s post-Fed low · resistance: 764.30 (20 SMA)
→ QQQ support: 713.24 (20 SMA) / 709.95 (50 SMA) · resistance: the June highs near 740
───────────────────────────────────────────
WHAT BREADTH SAYS
───────────────────────────────────────────
Every reading fell again. This week two important lines broke.
S5TH dropped to 49.50 from 56.46. For the first time in this report’s history, fewer than half of S&P 500 stocks are above their 200-day average. MMTH did the same, down to 47.95 from 51.68. Neither market is in a long-term bear, but both have lost their long-term majority.
The short end is close to washed out. S5FI fell to 27.83 from 38.76, less than three points above the 25 line. MMTW is at 26.82, MMFI at 34.02. Roughly three in four stocks are below their 20-day and 50-day averages.
New highs versus new lows fell to 0.20x from 0.65x. That’s five new lows for every new high.
The concentration gap is the reading to pay attention to. On the 50-day it’s now −6.19, from −0.89. The S&P 500 has weaker intermediate breadth than the broad market. Put that next to an S&P 500 that finished the week flat and the answer is plain: a handful of large names, mostly chipmakers, held the index up while most of its members fell. Friday said it outright. Most S&P 500 stocks went down and the index still closed green.
An index that holds up while its members fall is not a strong index. It’s a narrow one.
───────────────────────────────────────────
WHAT MACRO SAYS
───────────────────────────────────────────
The 10-year closed the week at 5.000%, with an intraday high at 5.008%. It traded above 5% for the first time since 2007 and closed there on Friday. The trend hasn’t paused. It’s been climbing since March.
VIX closed at 14.82 and sits below all four of its own averages. It jumped toward 18.5 around the Fed decision, then fell back once the hike was delivered. With breadth this weak, a VIX under 15 isn’t a sign of safety. It means nobody is paying for protection.
───────────────────────────────────────────
WHAT ROTATION SAYS
───────────────────────────────────────────
The board improved compared with last week, but the improvement sits in the same narrow group that’s holding up the index.
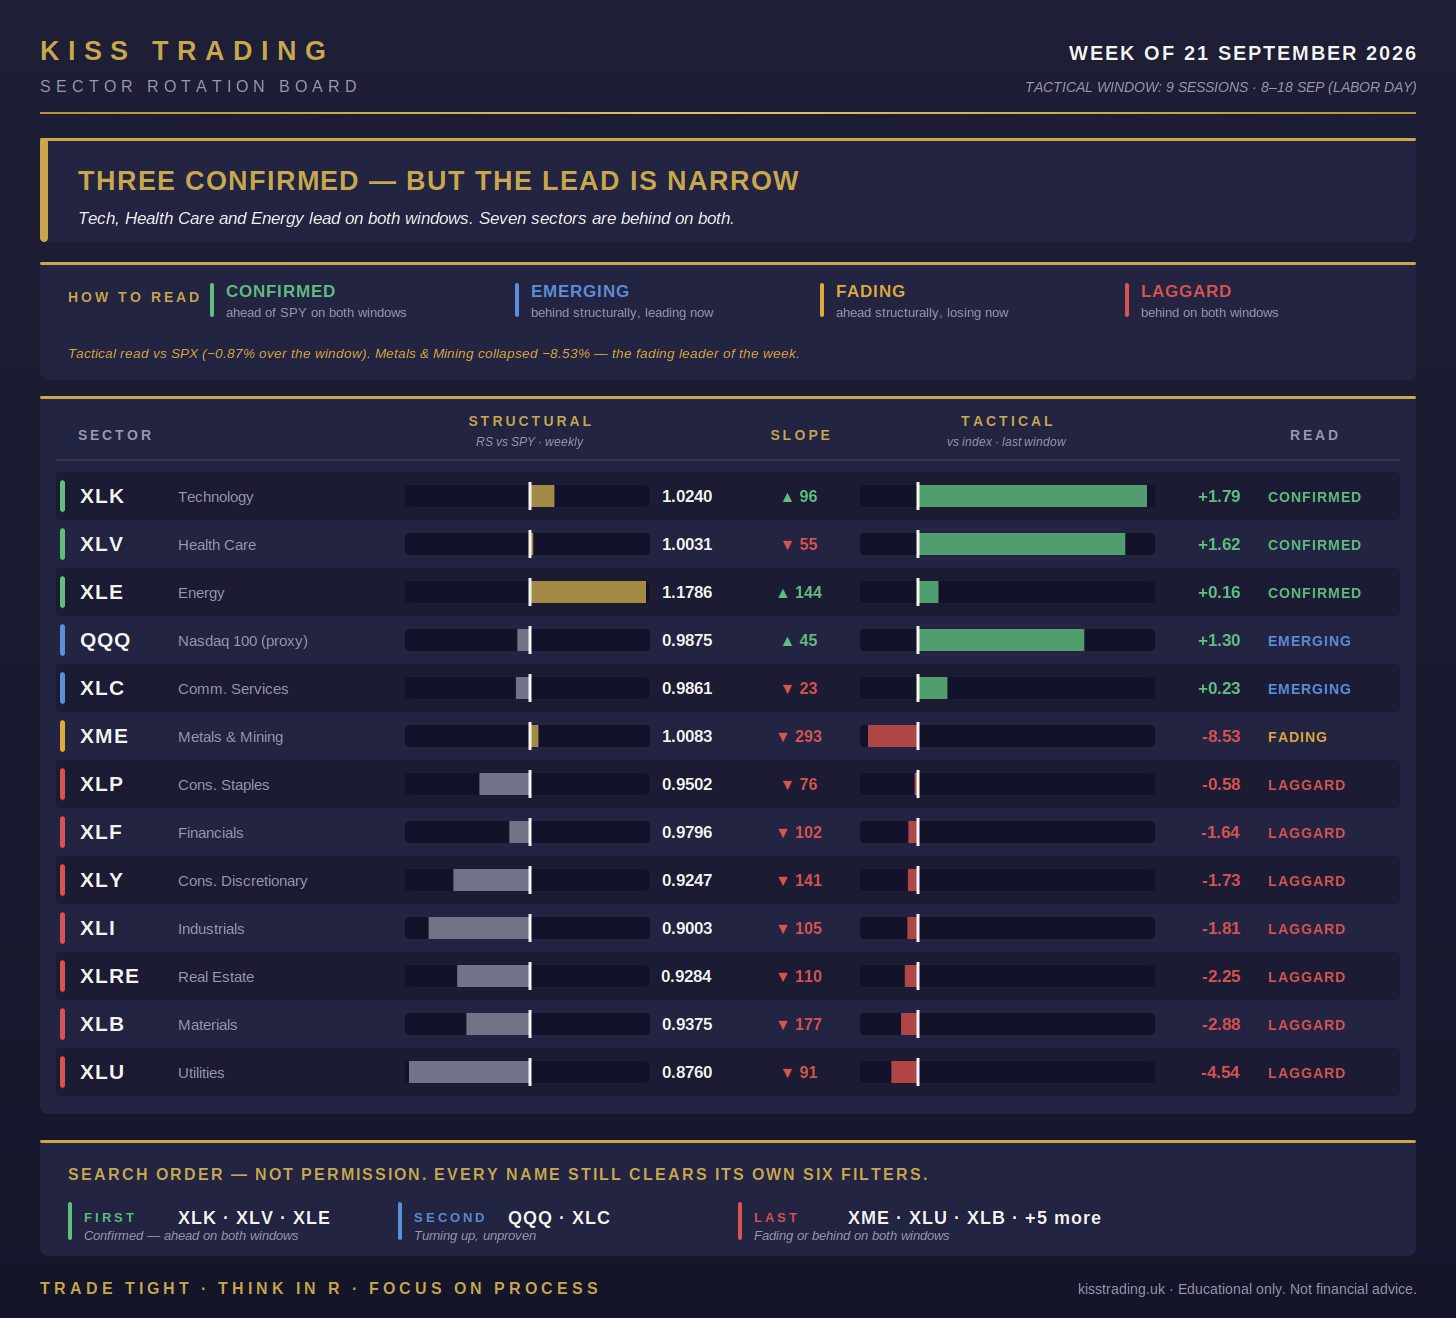
Three sectors are confirmed on both windows: Energy, Technology and Health Care. Technology is the real mover. It’s ahead of SPY structurally at 1.0240 and tactically at +1.79% over the window, with the second-strongest weekly acceleration on the board at +96. That’s the chip rally showing up in the tape. QQQ and Comm. Services moved into the emerging tier, behind structurally but leading now.
Energy is still the strongest structural leader (RS 1.1786, trend strength 34.3, the highest on the board), but its tactical lead has shrunk to just +0.16%. Oil fell three days in a row and ended the week roughly flat. Leadership is still there, but it has stopped extending.
Health Care is confirmed but has a flag: its weekly slope is −55. It’s ahead of SPY, and the gap is narrowing.
Metals & Mining is the collapse of the week. It lost 9.40% in absolute terms, 8.53% against SPY. It’s still barely above 1.0 structurally, but decelerating at −293 a week, by far the worst on the board. It’s a textbook fading leader.
Seven sectors are behind on both windows: Financials, Utilities, Staples, Real Estate, Industrials, Discretionary and Materials. Utilities lost 5.41% in the window. So the defensives didn’t absorb the selling either. This isn’t a rotation into safety. It’s a rotation into a few names.
The search order at the bottom of that board is only an order to search in. It’s not permission, and this week not even the order applies. The regime closes the door before any sector gets a vote.
───────────────────────────────────────────
MACRO — WHAT LAST WEEK DELIVERED
───────────────────────────────────────────
→ FOMC, Wednesday: +25bp to 3.75%–4.00%, a unanimous 12-0 vote, the first hike since July 2023. The dot plot’s year-end median is 4.00%–4.25%, which implies one more hike in 2026. Markets are pricing about 50% for October.
→ Retail sales (August), Wednesday: +1.2% vs +0.7% expected. Control group +1.4% vs +0.4%. July revised to −0.5%.
→ Jobless claims, Thursday: 196,000 vs roughly 207,000 expected. Continuing claims at 1.73 million, the lowest since early 2024.
→ Oil: Brent settled Friday at $103.87, down almost 1% on the week. WTI at $100.30, flat. Saudi Arabia’s East-West pipeline was shut after a drone strike, and Aramco is working to restore half its capacity.
→ Friday: quarterly options expiry, about $7 trillion in notional.
Fed funds: 3.75%–4.00%. Strong spending and low claims give the Fed no reason to stop. The hiking cycle has started and the data isn’t pushing back.
Geopolitics: the Iran–Gulf meeting on the Strait of Hormuz, scheduled for Monday in Oman, was postponed indefinitely the evening before. Hormuz traffic is still heavily restricted.
───────────────────────────────────────────
MACRO FLAGS — WEEK AHEAD
───────────────────────────────────────────
→ Wednesday 23 September, 09:45 ET: S&P Global flash PMIs (September)
→ Thursday 24 September, 08:30 ET: initial jobless claims
→ Friday 25 September, 08:30 ET: durable goods orders (August). 10:00 ET: University of Michigan final sentiment and inflation expectations
→ All week: Fed speakers after the hike. Watch the tone on October.
Calendar note: no CPI, FOMC or NFP this week, so the calendar doesn’t block any evening. It doesn’t matter, because the regime does. Looking ahead, next week has PCE on Wednesday 30 September and NFP on Friday 2 October. If the regime reopens, the last clean arming evening before payrolls is Wednesday the 30th.
───────────────────────────────────────────
VERDICT RATIONALE
───────────────────────────────────────────
BEARISH holds. This is exactly the kind of week where it would be easy to talk yourself out of it.
QQQ repaired its Stage 2. Nasdaq finished up. The S&P 500 bounced off 7,500 on Wednesday and recovered. If you only look at the index charts, it’s tempting to call the worst over.
The rule doesn’t look at one chart. SPY is still below its 20 SMA, so Stage 2 is still unmet on the index that counts first. None of the four conditions has cleared. And breadth is worse than it was when the verdict was issued: S5TH and MMTH both lost 50, and new lows outnumber new highs five to one. The one improvement came from a narrow group of large names. The rest of the market, the pool this system actually trades in, deteriorated.
What would upgrade this back to NEUTRAL: a SPY daily close above its 20 SMA at 764.30, with QQQ holding its Stage 2. That’s 0.34% away, close enough to happen on any single session. A close is what counts, not an intraday touch.
What would make it deeper: a SPY close below its 50 SMA at 759.73, 0.26% under Friday’s close. That would put the index below three of its four averages and move the conversation from no new entries to protecting what’s already open.
The four conditions, as they stand:
→ SPY closed below its 20 SMA — FIRED, 761.69 vs 764.30
→ Broad short-term breadth under 50 — FIRED, MMTW at 26.82
→ US 10-year above 4.75% decisively — FIRED, 5.000%, the highest close since 2007
→ A Middle East supply headline moving oil sharply higher — FIRED, Saudi pipeline shut, Brent above $100, Hormuz talks postponed
═══════════════════════════════════════════
WHAT HAPPENS TO THE WATCHLIST
═══════════════════════════════════════════
No Watchlist and no Trade Plan again this week.
The reason is the same as last week: when the regime says no new entries, a list of setups to arm is a list you’re not allowed to act on. Publishing it anyway would be process theatre.
It’s worth saying how the two weeks differ. Last week, everything was breaking together. This week, one index recovered and most stocks kept falling. That second picture is the more dangerous one, because it looks like permission. In a narrow market, a breakout on a name outside the leading group fills on a session with no one behind it, and the LVTD gate closes it at 15:55. That’s the cost a regime filter exists to avoid.
The Watchlist comes back on the Sunday after SPY closes above its 20 SMA. Not before.
───────────────────────────────────────────
Trade Tight · Think in R · Focus on Process
— Radu
KISS Trading
───────────────────────────────────────────
⚠️ Educational only. Not financial advice. Always DYOR.