
═══════════════════════════════════════════
WEEKLY REGIME VERDICT
═══════════════════════════════════════════
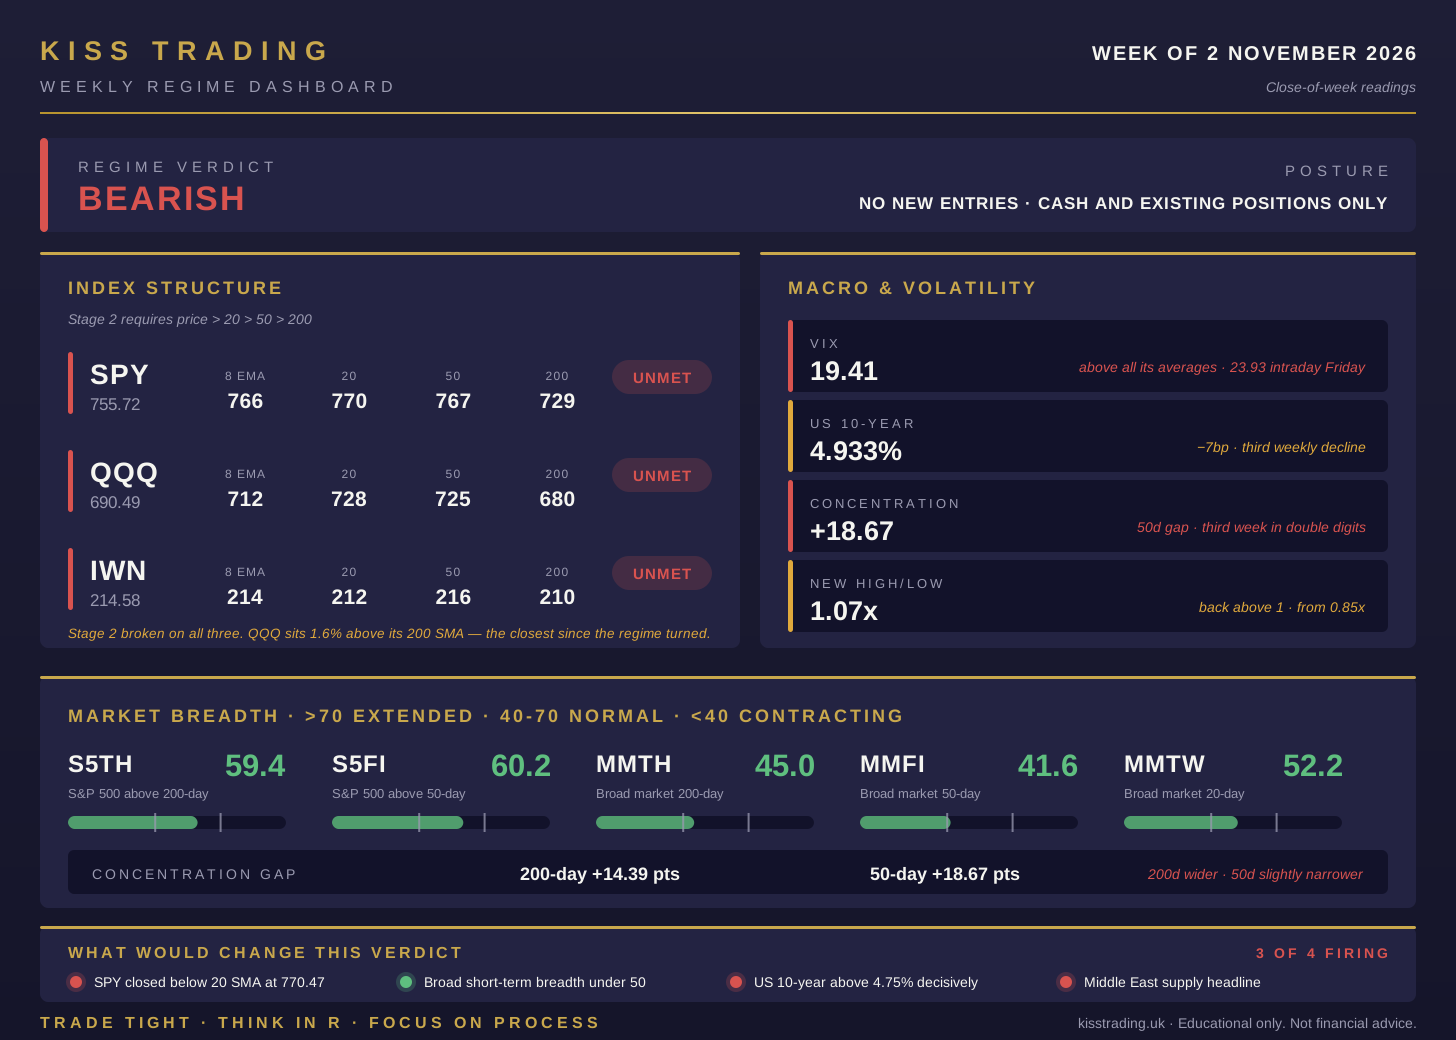
BEARISH
Posture: no new entries — cash and existing positions only
Held for a fourth week. Broad short-term breadth closed above 50, so one condition has cleared. SPY and QQQ are both still below their 20 SMAs, and the restoration test needs the index, not breadth.
For the first time since mid-October, one of the four lights went out. The index didn’t follow. Friday took back most of the week’s gains in one session, and it came from the same place as every other bad day this autumn: the stocks that carry the AI trade.
───────────────────────────────────────────
WHAT THE STRUCTURE SAYS
───────────────────────────────────────────
SPY lost half a percent on the week and never reached its 20 SMA. The 8 EMA, the 20 and the 50 still sit in a tight band above price, and the 8 is now below both of the others. That band is the ceiling until a close proves otherwise.
QQQ is the problem. It fell another 2% and closed 1.6% above its 200 SMA. That’s the closest it has been since the regime turned. A close below it would take the Nasdaq out of Stage 2 on every horizon, not just the short one.
IWN went the other way again. It’s up for a second week, above its 8 EMA and 20 SMA, and 0.6% under a 50 SMA that is still falling. The badge stays UNMET because the 20 is below the 50. It’s still the only index moving in the right direction.
Key levels for the week:
→ SPY: 770.47 (20 SMA) is the level that matters, 2.0% above Friday’s close · support at the 200 SMA, 728.85
→ QQQ: 728.19 (20 SMA) is 5.5% away · support at the 200 SMA, 679.52 — 1.6% below
───────────────────────────────────────────
WHAT BREADTH SAYS
───────────────────────────────────────────
Every bar finished higher than a week ago. MMTW closed at 52.22, the first close above 50 since the regime turned, and that clears condition 2. S5FI, S5TH, MMTH and MMFI all rose with it.
Friday is the caveat. Every breadth series fell between 5% and 13% in one session. MMTW had been near 60 midweek. The week was a broadening. Friday was the reminder that it isn’t settled.
The concentration gap moved in two directions. On the 200-day row it widened again, to +14.39. On the 50-day row it narrowed slightly, to +18.67. That’s the third week in double digits on both horizons. Large caps and the broad market are still on different stories.
New highs edged back above new lows, at 1.07x. Thin, but on the right side of 1.
───────────────────────────────────────────
WHAT MACRO SAYS
───────────────────────────────────────────
The 10-year fell for a third week, to 4.933%. Direction keeps helping. The level still sits almost two-tenths above the 4.75% line, so condition 3 stays on.
VIX finished flat on the week, but Friday’s intraday spike to 23.93 tells the real story. Hedges went back on hard into the close, and VIX is still above every one of its averages.
Oil stayed above $100. December crude closed near $103 on Friday, lifted by the risk of renewed US strikes on Iran. Condition 4 isn’t close to clearing.
───────────────────────────────────────────
WHAT ROTATION SAYS
───────────────────────────────────────────
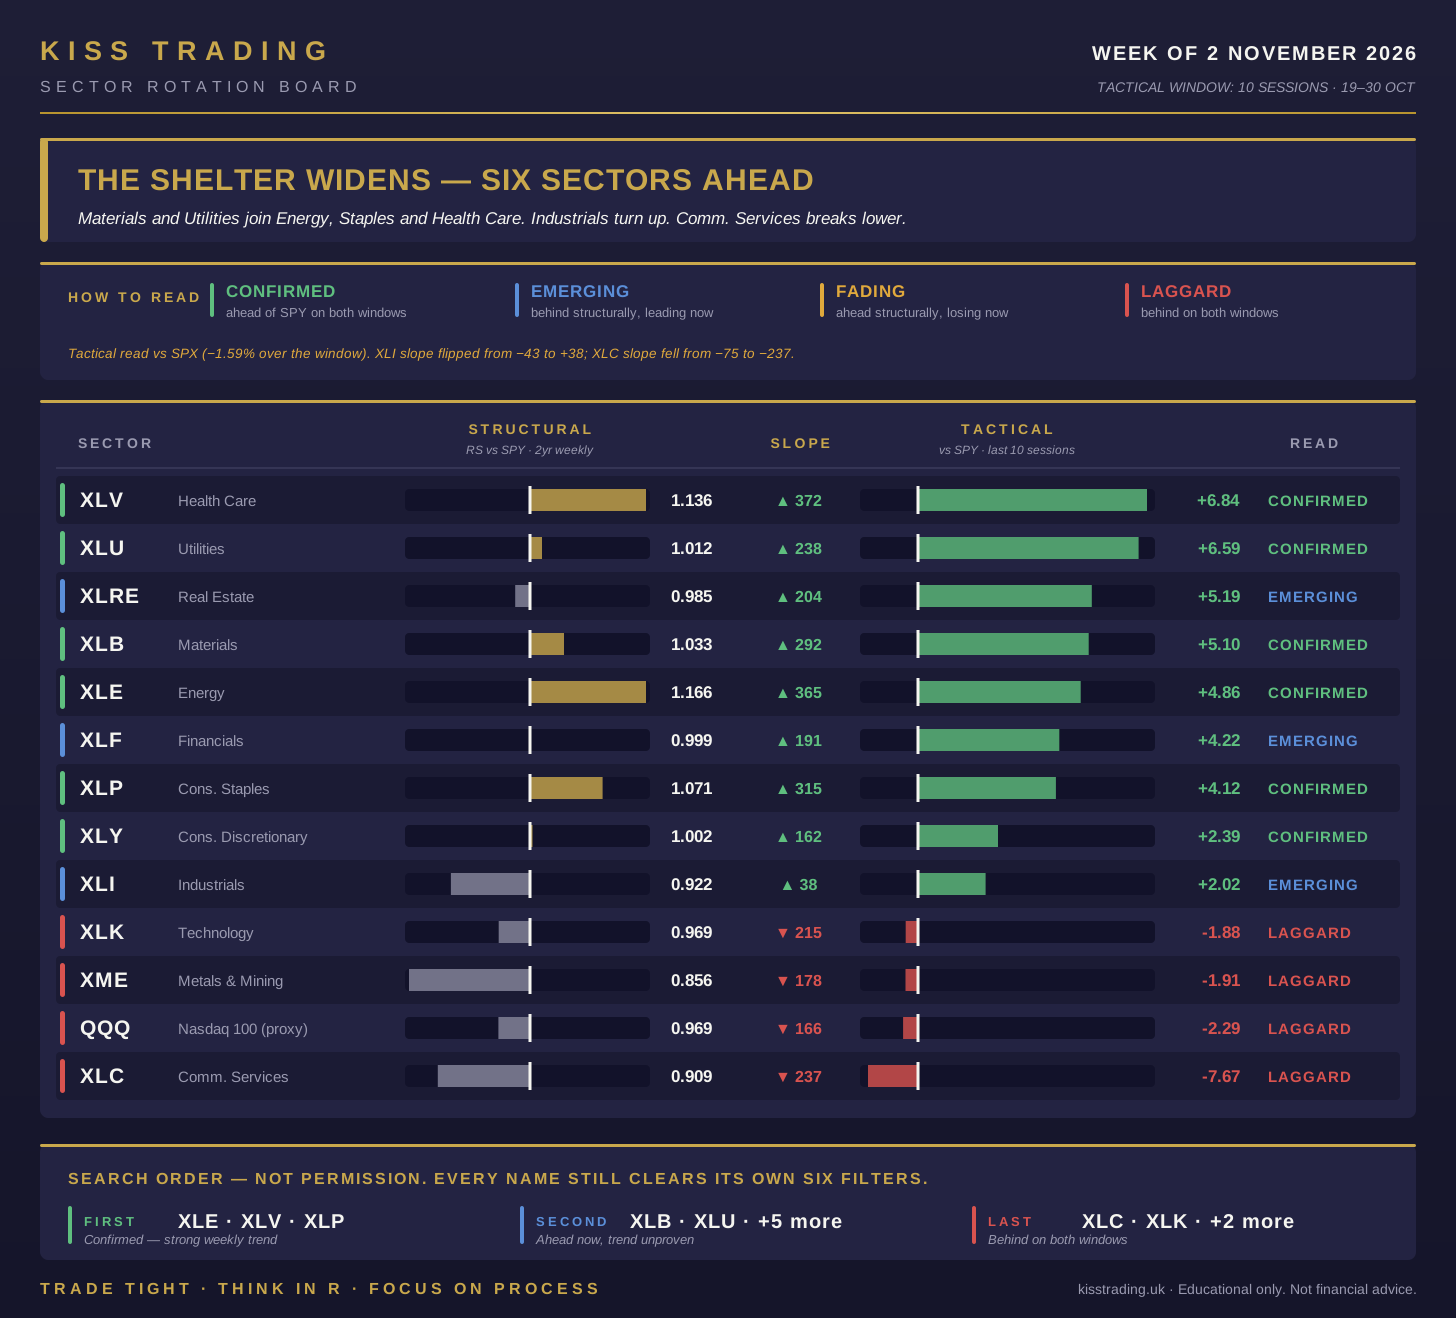
The shelter widened. Last week three sectors were confirmed. This week six are. Materials and Utilities moved up from EMERGING to CONFIRMED, and Consumer Discretionary crossed above 1.00, just barely, on a weekly trend too weak to trust. Health Care took the top of the tactical window at +6.84% against the index.
The divergence that matters is Industrials. A week ago it was a laggard on both windows. This week its slope turned positive and it’s ahead of SPY over ten sessions. That’s the first cyclical sector to turn in a month.
At the bottom, Communication Services fell hardest, −7.67% against the index over ten sessions, after Alphabet’s 12.6% drop on Thursday. Technology’s slope improved from −290 to −215. It’s still behind on both windows.
The search order at the bottom of that board is search order. It is not permission. Health Care, Materials and Energy have all run hard. Expect to look there first and find nothing armable — a sector up 5% to 7% against the index in ten sessions will fail the dynamic ceiling on almost every name inside it.
───────────────────────────────────────────
MACRO — WHAT LAST WEEK DELIVERED
───────────────────────────────────────────
→ FOMC, Wednesday: held at 3.75–4.00%, 10–2. Cook and Hammack dissented in favour of a hike.
→ Q3 GDP (advance), Thursday: 3.4% annualised, up from 2.2% in Q2.
→ PCE (September), Thursday: headline +0.5% m/m, 3.6% y/y. Core +0.3% m/m, 3.1% y/y.
→ Big tech, Wednesday–Thursday: Alphabet −12.6% on Thursday on negative free cash flow. Amazon missed on EPS and revenue. Intel guided Q4 well below estimates.
→ Friday: S&P 500 −1.82%, Nasdaq −2.86%. The money that left tech went to staples, health care and energy.
Fed funds: 3.75–4.00%. Strong growth and sticky inflation keep a December hike on the table.
Geopolitics: crude back above $100 on the risk of renewed US strikes on Iran.
───────────────────────────────────────────
MACRO FLAGS — WEEK AHEAD
───────────────────────────────────────────
→ Monday 2 November: ISM Manufacturing (October), 10:00 ET
→ Tuesday 3 November: JOLTS (September), 10:00 ET · US midterm elections
→ Friday 6 November: Employment Situation (October), 8:30 ET
Calendar note: Friday is an NFP session, which makes it a no-new-order day, so the last arming evening of the week is Wednesday, not Thursday. In a BEARISH regime that changes nothing. No orders are armed on any evening. If the regime is restored next Sunday, the calendar for the week of 9 November is checked fresh, and CPI lands on Tuesday 10 November.
───────────────────────────────────────────
VERDICT RATIONALE
───────────────────────────────────────────
BEARISH holds because the restoration test didn’t move. It needs a SPY close above its 20 SMA and QQQ back above its own. SPY finished further from its 20 than a week ago. QQQ finished further still.
Condition 2 cleared, and that is recorded. It’s the first condition to clear since the regime turned. It does not restore NEUTRAL on its own, and last week’s report said so before it happened. Breadth is recorded, never a gate.
What restores NEUTRAL: a SPY close above its 20 SMA at 770.47, together with QQQ back above its 20 SMA at 728.19. SPY is 2.0% away. QQQ is 5.5% away.
What would make it worse: QQQ losing its 200 SMA at 679.52, 1.6% below Friday’s close. Then SPY losing its own at 728.85, 3.6% below.
The four conditions, as they stand:
→ SPY closed below its 20 SMA — FIRED, 755.72 vs 770.47
→ Broad short-term breadth under 50 — CLEARED, MMTW at 52.22
→ US 10-year above 4.75% decisively — FIRED, 4.933%, falling for a third week
→ A Middle East supply headline moving oil sharply higher — FIRED, crude above $100 on the risk of renewed strikes on Iran
═══════════════════════════════════════════
WHY THERE IS NO WATCHLIST THIS WEEK
═══════════════════════════════════════════
Paid subscribers will not receive a Watchlist or a Trade Plan this Sunday. This is the third week in a row, for the same reason.
A BEARISH verdict means no new entries. The scan keeps running in the background. Six sectors are now ahead of the index, more than at any point since the regime turned. When it does turn, the list will not be short of candidates.
This week tested the rule from the other side. A condition cleared, breadth broadened, yields fell again. It would be easy to call that enough. But the index closed lower, and the Nasdaq is now closer to its 200-day than to its 20-day. The system doesn’t upgrade on improvement. It upgrades on the close that proves it.
Cash is a position. For one more week, it’s the only one the system allows.
═══════════════════════════════════════════
WHAT’S COMING NEXT WEEK
═══════════════════════════════════════════
v3.101 is going under review.
Next Sunday we announce how the system evolves — built on eleven years of backtested data, not on how the last four weeks felt.
The rules that run today stay in force until then. Nothing changes mid-week, and nothing changes because the tape is uncomfortable. When it changes, you’ll see the evidence first.
───────────────────────────────────────────
Trade Tight · Think in R · Focus on Process
— Radu
KISS Trading
───────────────────────────────────────────
⚠️ Educational only. Not financial advice. Always DYOR.