
═══════════════════════════════════════════
WEEKLY REGIME VERDICT
═══════════════════════════════════════════
BEARISH
Posture: no new entries — cash and existing positions only
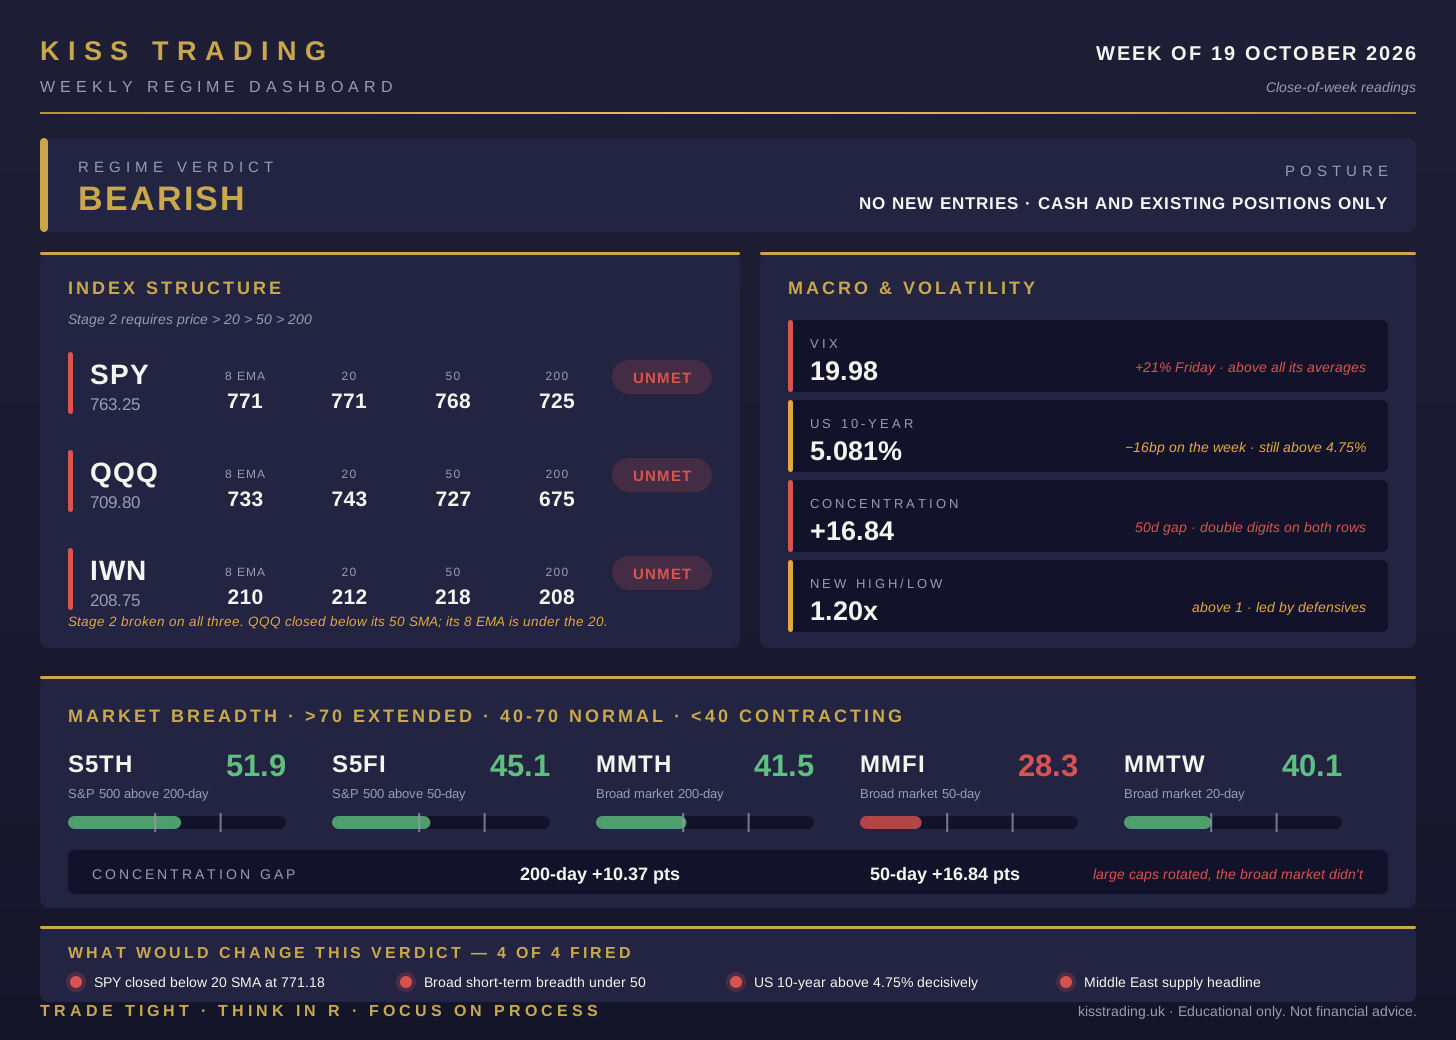
Changed on Wednesday 14 October, and confirmed by Friday’s close. SPY closed below its 20 SMA, the last of the four conditions still standing. All four are now firing, and Stage 2 is broken on SPY, QQQ and IWN.
Last Sunday, Technology was the only sector leading on both windows. By Friday it was the weakest group on the board. The leaders didn’t drift lower with the market. They left first, and capital moved into staples, energy, health care and utilities on the way out.
───────────────────────────────────────────
WHAT THE STRUCTURE SAYS
───────────────────────────────────────────
SPY closed at 763.25, down 2.0% on the week. It sits below the 8 EMA at 771.34, the 20 SMA at 771.18 and the 50 SMA at 768.50, with only the 200 SMA at 725.01 still underneath. The squeezed stack flagged two weeks running finally gave way.
QQQ fell 5.5% in a week, the Nasdaq’s worst since June. At 709.80 it is below its 50 SMA at 726.77, and its 8 EMA has crossed under the 20. That’s the first index-level break in the short-term engine since the summer.
IWN is at 208.75, fifty cents above its 200 SMA, and below every other average. Small-cap value has now lagged for seven straight weeks.
Key levels for the week:
→ SPY: 771.18 (20 SMA) is the level that matters, 1.0% above Friday’s close · support at the 200 SMA, 725.01
→ QQQ: 742.52 (20 SMA) is 4.6% away · support at the 200 SMA, 674.91
───────────────────────────────────────────
WHAT BREADTH SAYS
───────────────────────────────────────────
At first glance, S&P 500 breadth improved. S5FI rose from 34.93 to 45.12 and S5TH from 47.70 to 51.88, while the index fell 2%. That combination only happens one way: money leaving a handful of large leaders and spreading across the rest of the index. Defensive stocks climbed back above their averages while tech fell through its own.
The broad market didn’t join in. MMTH slipped to 41.51 and MMFI to 28.28. MMTW recovered to 40.12, still ten points short of 50.
That opens the concentration gap to +10.37 on the 200-day row and +16.84 on the 50-day. Double digits on both horizons is the first time this report has recorded it. It means large-cap index members and the broad market are moving on different stories: the first is rotating, the second is still contracting.
New highs outnumbered new lows on Friday, 1.20x, for the first time in weeks. The new highs came from energy, staples and utilities. That’s not a market turning up. It’s a market hiding.
───────────────────────────────────────────
WHAT MACRO SAYS
───────────────────────────────────────────
The inflation data ran hot across the board. CPI on Wednesday: headline 3.7% annual against 3.6% expected, core 2.6% against 2.5%. PPI on Thursday: +1.3% in a month against 0.5% expected. Gasoline was the common driver in both.
The 10-year touched 5.33% on the CPI print, then fell to 5.081% by Friday as money moved into safety. Down 16 basis points on the week. On the macro panel that’s direction over level, and direction finally turned. It doesn’t touch condition 3, which is about level, and 5.08% is still a third of a point above 4.75%.
VIX closed at 19.98, up 21% on Friday alone, after touching 22.31 intraday. For four weeks it sat below all of its averages and we called that an absence of hedging. This week the hedging arrived.
───────────────────────────────────────────
WHAT ROTATION SAYS
──────────────────────
─────────────────────
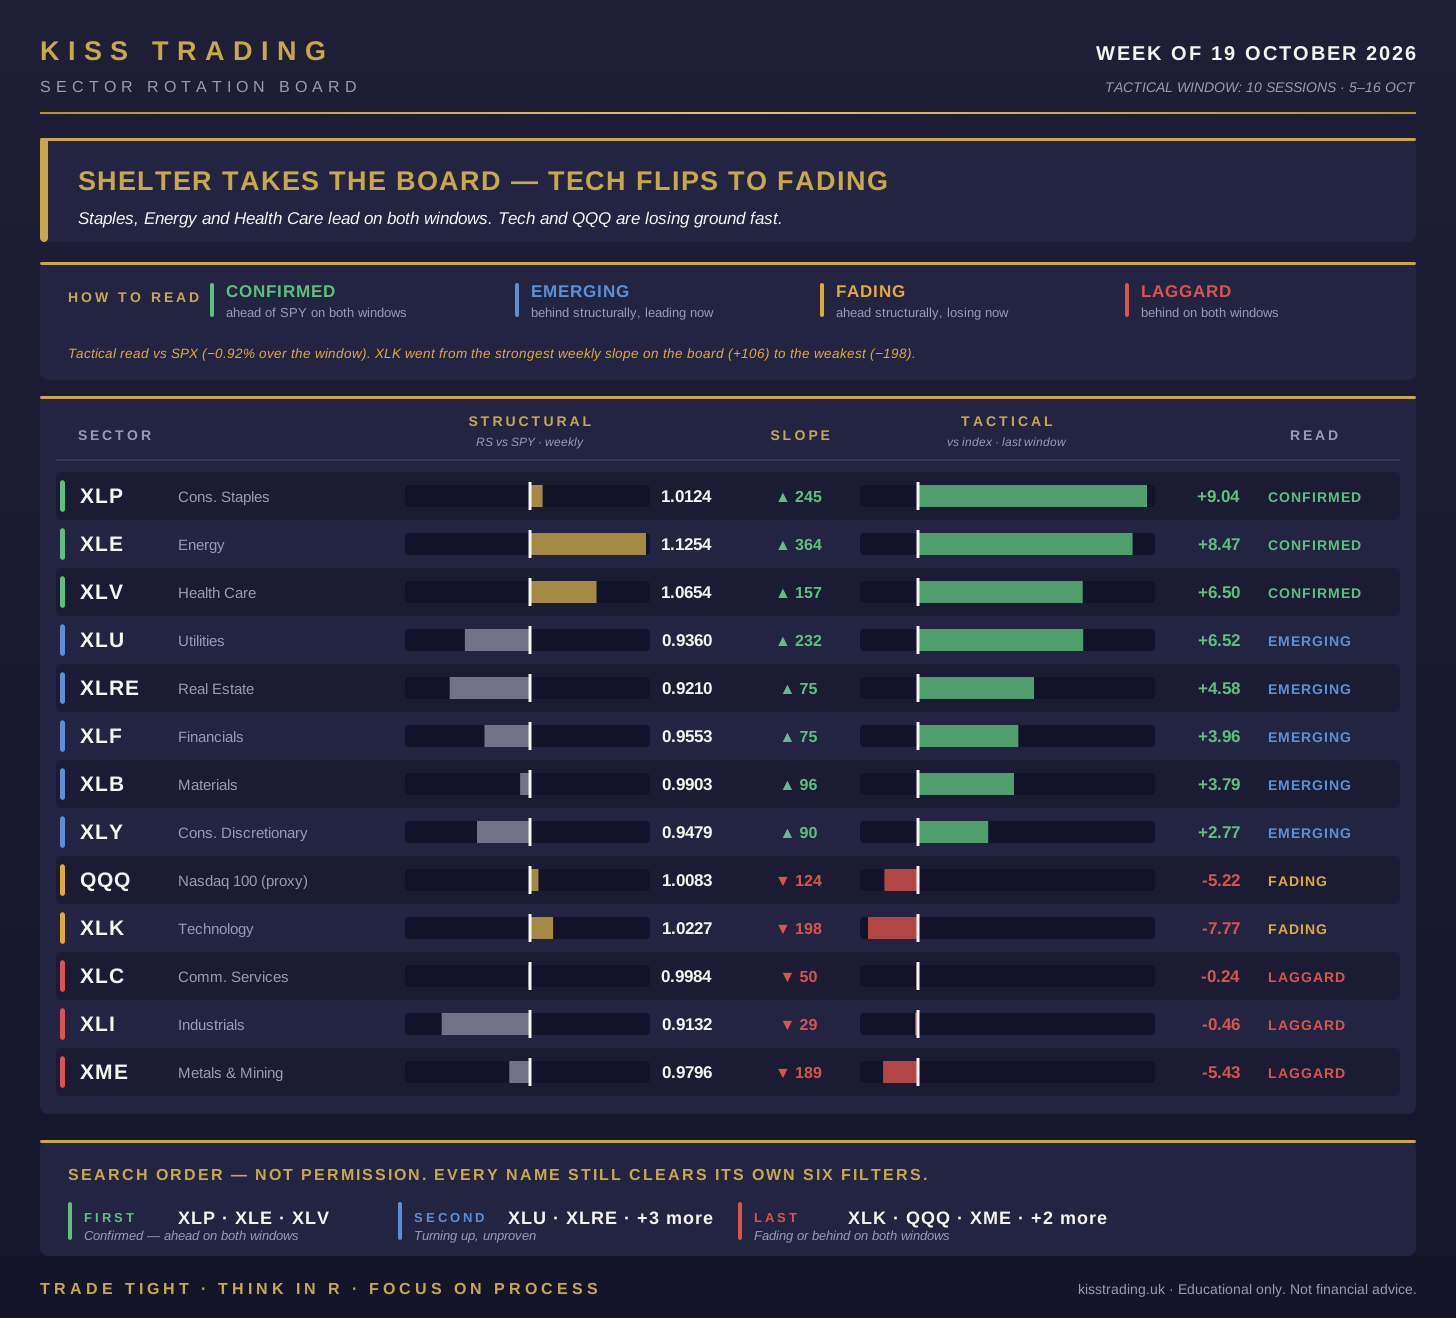
Three sectors are confirmed on both windows, and none of them is growth. Staples lead the window at +9.04% against the index. Energy follows at +8.47% with the steepest acceleration on the board, +364 a week. Health Care is back, confirmed at +6.50%.
Five more are emerging, led by Utilities at +6.52%. Real Estate, Financials, Materials and Discretionary are all ahead of the index tactically while still behind structurally.
Technology flipped to fading. XLK is still above SPY structurally at 1.0227, but it lost 7.77% against the index in ten sessions. A week ago its slope was +106, the strongest on the board. Now it is −198, the weakest. QQQ is fading alongside it. The trigger was AI financing: debt worries around a major AI infrastructure lender spread into semiconductors, and the Philadelphia Semiconductor Index fell for eight straight sessions.
In a BEARISH regime the board isn’t a search order. Nothing is being armed. It’s a record of where capital went when it stopped wanting risk.
───────────────────────────────────────────
MACRO — WHAT LAST WEEK DELIVERED
───────────────────────────────────────────
→ CPI (September), Wednesday: +0.6% monthly, 3.7% annual vs 3.6% expected. Core +0.3% monthly, 2.6% annual vs 2.5%. Gasoline +9.1% in a month; energy +20.4% on the year.
→ PPI (September), Thursday: +1.3% monthly vs 0.5% expected, 6.3% annual. Core +0.5% monthly.
→ Retail sales (September), Thursday: +0.8% vs 0.3% expected — but the control group rose only 0.1% against 0.3%. Shoppers paid more for fuel and less for everything else.
→ Fed: Chair Warsh gave no signal on the late-October meeting. October hike odds rose to roughly 37% after CPI and fell back to about 17% by Friday. December hike odds near 89%.
→ Oil: Brent closed Friday near $109.86, its highest close since May, after renewed tanker attacks around the Strait of Hormuz. WTI above $101.
→ Indices: S&P 500 −2.0% on the week. Nasdaq Composite −4.5%. Dow +0.7%.
───────────────────────────────────────────
MACRO FLAGS — WEEK AHEAD
───────────────────────────────────────────
→ Tuesday 20 October, after the close: Netflix earnings
→ Wednesday 21 October, after the close: Tesla and Meta earnings
→ Tuesday–Wednesday 27–28 October: FOMC decision, the week after next
Calendar note: no CPI, FOMC decision or payrolls this week. In a BEARISH regime that changes nothing — no orders are armed on any evening. If the regime is restored next Sunday, FOMC Wednesday 28 October becomes a no-new-order session, and Tuesday 27 October is not an arming evening.
───────────────────────────────────────────
VERDICT RATIONALE
───────────────────────────────────────────
BEARISH holds because the test that grants NEUTRAL is failing on every index. SPY is below its 20 SMA. QQQ is below its 50. IWN is resting on its 200. The four conditions all fire, and none of them is close to clearing except the first.
Two readings improved. Yields fell 16 basis points, and new highs outnumbered new lows. Neither is a gate. Breadth is recorded, never a gate; macro sets context, not the verdict. Both improvements also came from the same source: money running to safety. Falling yields and defensive new highs are what fear looks like in a strong economy.
What restores NEUTRAL: a SPY close back above its 20 SMA at 771.18, together with QQQ back in Stage 2, which requires a close above its 20 SMA at 742.52. SPY is 1.0% away. QQQ is 4.6% away. One green session will not do it for both.
What would make it worse: SPY losing the 200 SMA at 725.01. That’s not one of the four conditions. It would mean the long-term trend itself had turned, and the cash posture would stay in place for longer than a week or two.
The four conditions, as they stand:
→ SPY closed below its 20 SMA — FIRED, 763.25 vs 771.18
→ Broad short-term breadth under 50 — FIRED, MMTW at 40.12
→ US 10-year above 4.75% decisively — FIRED, 5.081%, though falling
→ A Middle East supply headline moving oil sharply higher — FIRED, Brent at its highest close since May on renewed Hormuz attacks
═══════════════════════════════════════════
WHY THERE IS NO WATCHLIST THIS WEEK
═══════════════════════════════════════════
Paid subscribers will not receive a Watchlist or a Trade Plan this Sunday. That isn’t a missed week. It’s the system working as designed.
A BEARISH verdict means no new entries. Publishing triggers for setups the rules forbid you to take would turn the watchlist into a wish list. The scan still runs, and the names that hold their structure through this will be the first ones on the list when the regime turns back.
Last week showed why the rule exists. Two of the names on Sunday’s list filled on Monday. Both failed the volume gate at 15:45 and were sold at 15:55 for a combined −0.56R. One of them rallied afterwards, and the CPI calendar rule kept us out of the rebound. It cost us that trade. Two days later the market broke, and the same rules kept us out of everything else.
Cash is a position. This week it’s the only one the system allows.
───────────────────────────────────────────
Trade Tight · Think in R · Focus on Process
— Radu
KISS Trading
───────────────────────────────────────────
⚠️ Educational only. Not financial advice. Always DYOR.