
═══════════════════════════════════════════
WEEKLY REGIME VERDICT
═══════════════════════════════════════════
BEARISH
Posture: no new entries — cash and existing positions only
Downgraded from NEUTRAL. All four invalidation conditions have now fired, and Stage 2 is broken on both SPY and QQQ.
This is the first BEARISH call this system has produced. Everything below explains why, and why the response is mechanical rather than a judgement call.
───────────────────────────────────────────
WHAT THE STRUCTURE SAYS
───────────────────────────────────────────
A week ago, SPY holding its 20 SMA was the last condition still standing. It is not standing now.
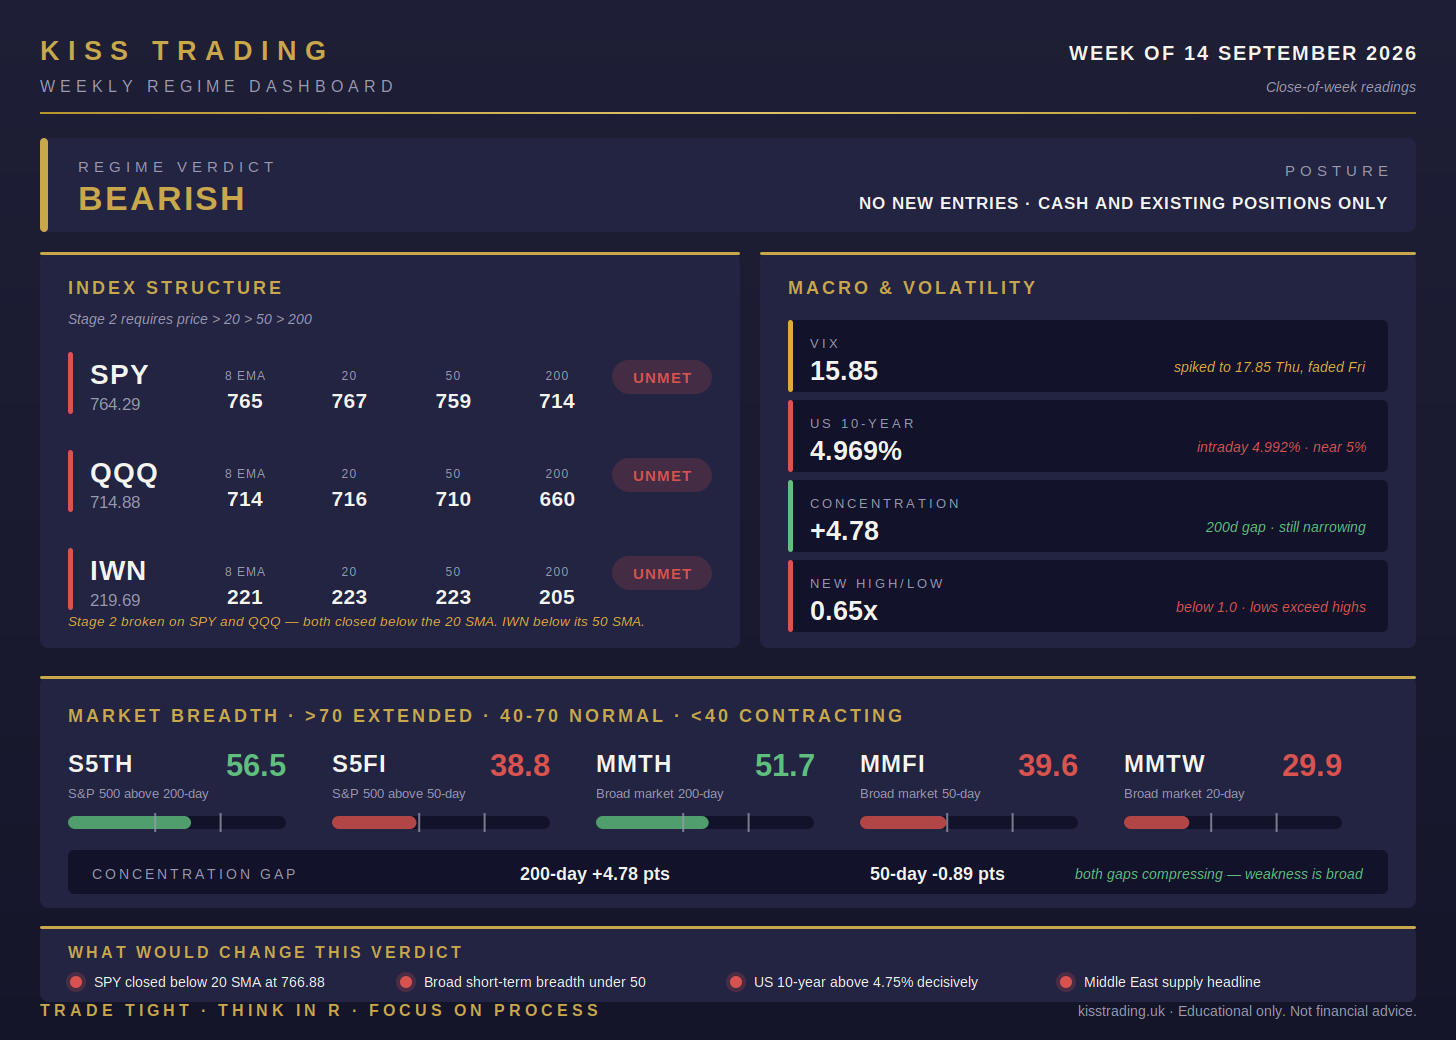
SPY closed at 764.29 against a 20 SMA at 766.88 — below it, and below the 8 EMA at 764.55 as well. QQQ did the same thing: 714.88 against a 20 SMA at 715.67. Both indices are still above their 50 and 200 day averages, so this is not a trend reversal. But Chapter 2’s test is price above the 20, above the 50, above the 200, and neither index passes it now.
That is the whole ballgame for entries. The system does not deploy capital when SPY and QQQ fail to confirm. Not a smaller size, not the cleanest setup only — no new entries.
IWN is further gone. At 219.69 it sits below its 8 EMA at 221.37, below the 50 SMA at 222.85, and below the 20 SMA at 223.43. Small caps broke first and broke hardest, which is the usual order.
One thing worth being clear about: Friday was a green session. SPY closed up 0.85%, QQQ up 0.87%. The rally did not reclaim anything. A bounce that leaves you below the 20 SMA is a bounce inside a broken structure, not a repair of it.
───────────────────────────────────────────
WHAT BREADTH SAYS
───────────────────────────────────────────
Every single reading fell, and three of the five are now in contraction territory.
MMTW dropped to 29.94 from 45.63. Seven out of ten broad-market stocks are below their own 20-day average. That is not a pullback in leadership, that is most of the market going down together. S5FI fell to 38.76 from 46.71, breaking the 40 line — fewer than four in ten S&P names hold their 50-day. MMFI at 39.65 did the same thing from 50.31.
The longer-horizon readings held up better. S5TH at 56.46 and MMTH at 51.68 are both down but still above 50, which is what separates this from a structural bear market. The damage is in the near term, and it is broad.
Two things sit underneath those headline numbers.
The concentration gap kept narrowing — 200-day gap at +4.78 from +6.31, the 50-day gap now essentially closed at −0.89 from −3.60. Normally that reads as healthy. It does not read that way here. The gap is closing because large caps are falling toward the broad market, not because the broad market is catching up. Convergence in a decline is not the same signal as convergence in an advance.
New highs versus new lows fell to 0.65x from 2.18x. Below 1.0 means more stocks are making new lows than new highs. That reading has not been below 1.0 at any point in the readings this system has published.
───────────────────────────────────────────
WHAT MACRO SAYS
───────────────────────────────────────────
The 10-year closed at 4.969%, with an intraday print of 4.992%. A week ago it was 4.784%. That is nearly nineteen basis points in five sessions, and it puts the yield within a third of a basis point of 5%.
August CPI landed Friday and it is the reason. Headline rose 0.4% month over month and held at 3.4% annually, both as expected. Core came in at 0.3% against a 0.2% forecast — only nine of seventy-three economists surveyed by Bloomberg had that number. Gasoline surged 3.9% and accounted for more than a third of the monthly increase, feeding straight through from the oil move.
Rate-hike odds for the 16 September FOMC went from roughly 48% in mid-August to 85.6% by Friday. The market has moved from a coin flip to treating a hike as the base case in one month.
VIX is the odd reading. It closed at 15.85, down 11.2% on the day, after closing near 17.85 on Thursday. So volatility spiked as the 10-year went through 4.9%, then collapsed on Friday’s relief rally. A VIX under 16 with breadth at these levels is not a sign of safety — it is a sign that protection is cheap because nobody has bought it yet.
───────────────────────────────────────────
WHAT ROTATION SAYS
───────────────────────────────────────────
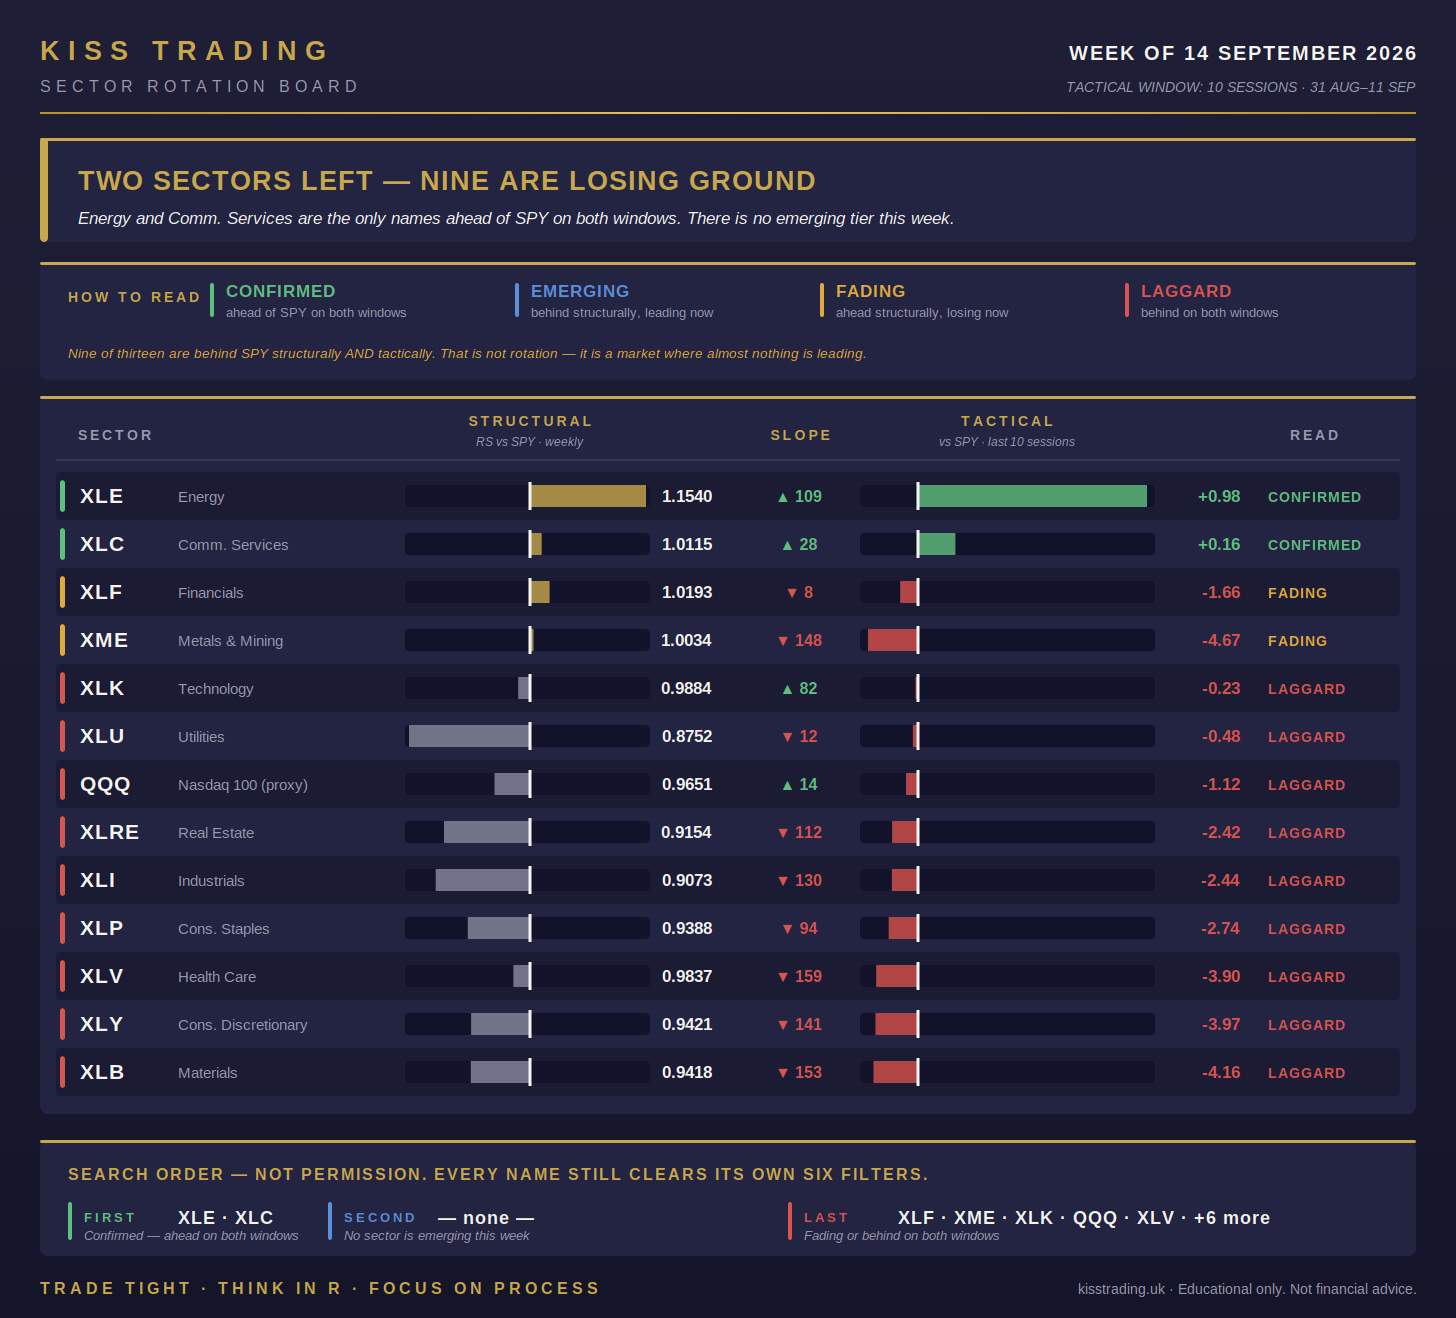
Two sectors are confirmed on both windows. Nine are losing ground on both. There is no emerging tier at all this week — not one sector that is behind structurally but gaining tactically.
Energy is the only genuine leader, and it is a big one: RS 1.1540 against SPY, accelerating at +109 a week, trend strength the highest on the board. Brent gained 8.7% on the week and WTI 9.4%, peaking near $108 and $104 before easing Friday on news that Iran and Gulf states will meet in Oman about the Strait of Hormuz. Saudi Arabia shut its East-West pipeline as a precaution. That is the sector and the story in one line.
Comm. Services is the second confirmed name, barely — RS 1.0115, tactical +0.16%. It is ahead by a rounding error rather than by conviction.
Technology is the interesting failure. Its weekly slope is +82, the second-strongest acceleration on the board, but its structural RS sits at 0.9884 and it lost 0.23% against SPY over the last ten sessions. A week ago Tech was the sharpest emerging signal in the scan, up 4.40% tactically. That reversed completely in five sessions. Whatever was carrying it was not broad.
Health Care is the worst deceleration at −159 a week, with Materials, Discretionary and Industrials all worse than −129. Those four plus Real Estate and Staples are behind SPY on both measures and falling away from it.
A board with nine laggards and no emerging tier is not telling you where to look. It is telling you there is nowhere to look.
───────────────────────────────────────────
MACRO — WHAT LAST WEEK DELIVERED
───────────────────────────────────────────
→ CPI, Friday: headline +0.4% monthly and 3.4% annual, both in line. Core +0.3% against +0.2% expected, annual core 2.4% — the smallest since spring 2021, but the monthly print is what moved rates. Gasoline +3.9%, over a third of the total increase. Housing +0.3%, the most in three months.
→ Oil, all week: Brent +8.7%, WTI +9.4%. Brent peaked near $108 Thursday, WTI above $104, before Friday’s pullback on the Oman talks. Saudi Arabia shut the East-West pipeline; Houthi forces reportedly advanced to Perim Island.
→ Rates: 10-year at 4.969%, intraday 4.992%.
Fed funds: 3.50%–3.75%. CME FedWatch now prices an 85.6% chance of a 25bp hike on 16 September.
───────────────────────────────────────────
MACRO FLAGS — WEEK AHEAD
───────────────────────────────────────────
→ Tuesday 15 – Wednesday 16 September: FOMC. Decision Wednesday 14:00 ET, press conference 14:30 ET. NO NEW BUY STOPS Wednesday — cancel by Tuesday’s close under the calendar rule.
→ Friday 18 September: monthly options expiration.
→ Monday 14 September: Gulf Cooperation Council diplomats meet their Iranian counterpart in Oman on the Strait of Hormuz.
The whole week is bracketed. Even if the regime permitted entries, Wednesday is blocked by the calendar rule and Friday is opex. And the Oman meeting Monday is the single headline most likely to move the oil condition in either direction.
What the Fed says on Wednesday matters more than what it does. An 85.6% priced hike is not a surprise. Whether Warsh frames it as one-and-done or as the start of a sequence is what repricies the 10-year, and the 10-year is what has been driving equities for three weeks.
───────────────────────────────────────────
VERDICT RATIONALE
───────────────────────────────────────────
The downgrade is mechanical, not discretionary.
Two weeks ago one condition had fired. Last week three had, and the report said plainly that the distance to the next downgrade had shrunk to almost nothing — SPY was holding its 20 SMA by roughly a tenth of a percent. This week it closed below it. That is the fourth condition, and it arrived alongside Stage 2 breaking on both indices.
There is no interpretation required here, and that is the point of writing the conditions down in advance. When they were set, the purpose was to remove the argument that always shows up at exactly this moment — the one that says the selloff is overdone, the bounce Friday was strong, the 200-day is still far below. All of that may be true. None of it changes what the four conditions say.
What this does not mean: it does not mean a crash is coming, and it does not mean selling everything. Both indices are still above their 50 and 200-day averages. Existing positions keep their Retest Shields and are managed exactly as planned. The change is narrow and specific: no new entries until the structure repairs.
What would upgrade this back to NEUTRAL: SPY reclaiming and holding its 20 SMA at 766.88, which is 0.34% away. That is the first thing to watch, and it is close enough to happen on any single session.
What would take it lower: SPY losing the 50 SMA at 758.62, roughly 0.75% below Friday’s close. That would put the index below three of its four averages and change the conversation from no-new-entries to protecting what is open.
The four conditions, as they stand:
→ SPY closed below its 20 SMA at 766.88 — FIRED, closed 764.29
→ Broad short-term breadth under 50 — FIRED, MMTW at 29.94
→ US 10-year above 4.75% decisively — FIRED, 4.969% with an intraday 4.992%
→ A Middle East supply headline moving oil sharply higher — FIRED, Brent +8.7% on the week
═══════════════════════════════════════════
WHAT HAPPENS TO THE WATCHLIST
═══════════════════════════════════════════
There is no watchlist this week, and no Trade Plan.
That is not a gap in the publishing schedule. It is the system working. When the regime says no new entries, producing a list of setups to arm would be publishing something you are not permitted to act on — which is how process discipline quietly becomes process theatre.
For the record, last week’s five names are all dead independently of the regime: CRWD and DLO closed below their 8 EMAs with MACD reversing, MD failed on volume dry-up at 99% of average, OSCR broke the dynamic ceiling, and PARR was left with two cents of headroom after its ratchet. Every one of them failed on its own numbers before the regime call was made.
Next Sunday the scan runs as normal. If SPY reclaims 766.88 and holds it, the watchlist comes back with it.
───────────────────────────────────────────
Trade Tight · Think in R · Focus on Process
— Radu
KISS Trading
───────────────────────────────────────────
⚠️ Educational only. Not financial advice. Always DYOR.